Contents
A party of ten that never arrives leaves a laid section earning nothing, after the kitchen has already bought and prepped for it. Taking no deposit means absorbing that loss in silence; taking one badly — an amount revealed late, a blanket no-refund line, terms the guest never saw before paying — turns the protection into card disputes, review damage and terms that cannot be relied on. UK unfair-terms law judges the wording a restaurant publishes, not the intention behind it. The deposit is rarely the problem; the rules the guest never agreed to are — so what do fair, workable deposit terms look like?
A restaurant booking deposit is paid by card when the table is reserved, after the guest has seen the amount and the terms. On arrival it is credited against the bill or returned; if the guest cancels in time, or the restaurant cancels, it is refunded in full. After a late cancellation or no-show, the restaurant may keep only what its published terms fairly allow — under CMA guidance, a genuine estimate of its direct loss.
How do restaurant deposits work?
Seen from the guest's side, a deposit is simple: choose a date, time and party size, see the amount and the conditions, pay by card in the same booking flow, and receive a confirmation that records what was paid and on what terms. From the restaurant's side, the same payment is a commitment device — money taken when the table is promised rather than when the meal is eaten, received directly by the restaurant, and held against a booking that now carries a real cost to abandon.
What happens to the money afterwards depends entirely on terms the restaurant set in advance. Two arrangements are common: the deposit is credited against the final bill on arrival, or it is held and returned after the meal. Either is workable, provided the guest was told which one applies before paying. If the guest cancels inside the notice period, or never arrives, the restaurant may retain some or all of it — but only in the way its published terms describe.
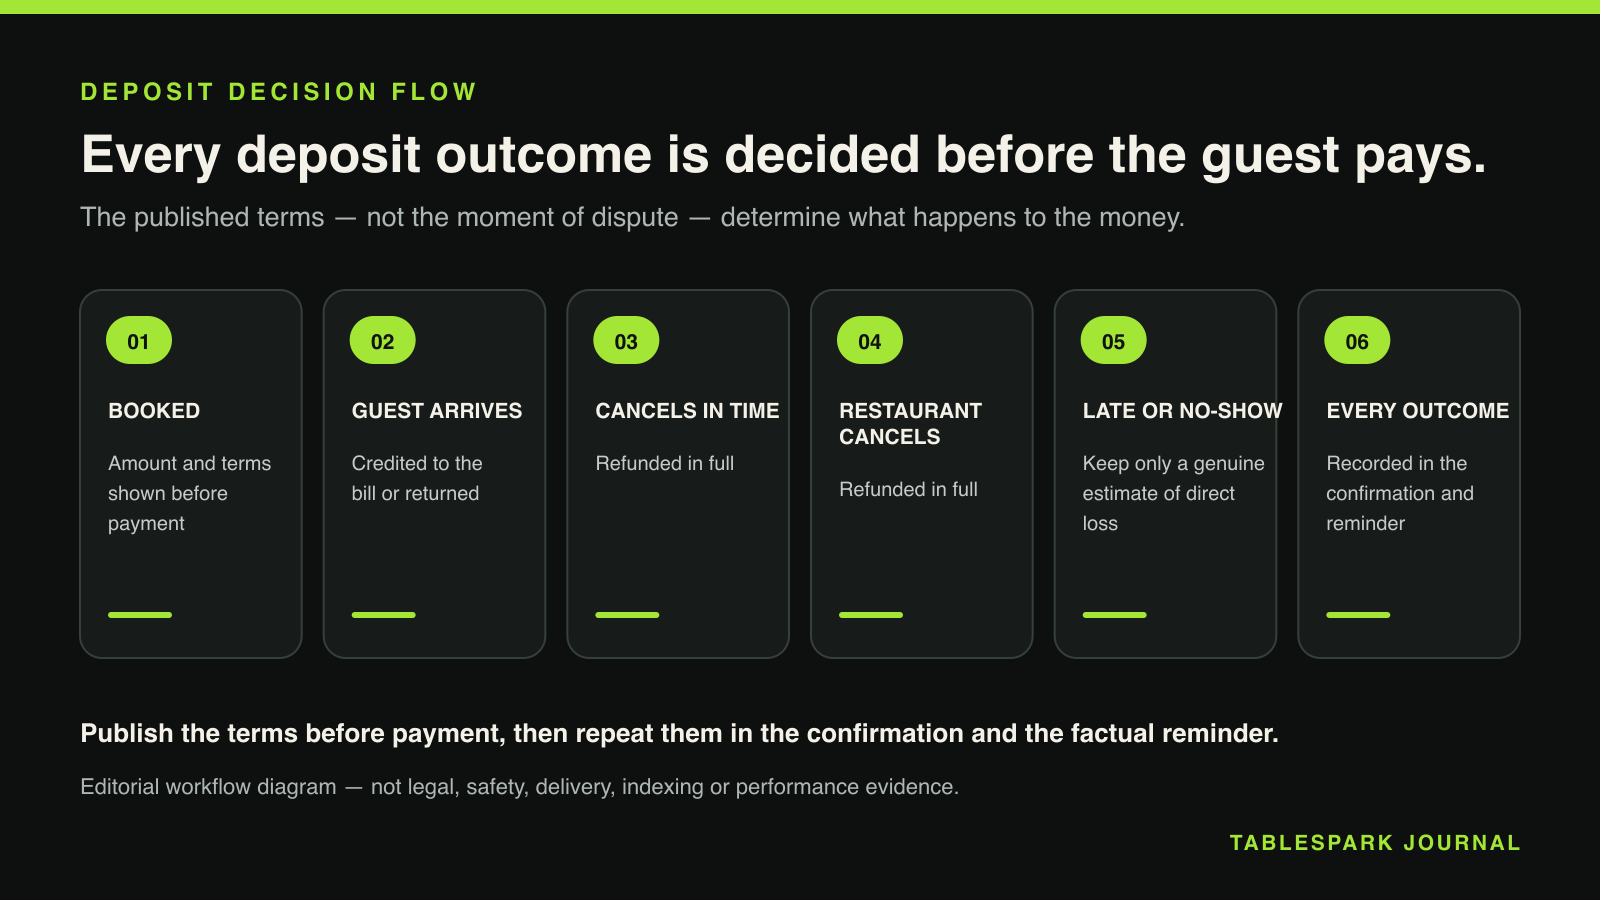
The diagram above shows the whole subject in one picture: every branch (credited, returned, refunded, retained) was decided at the moment the guest paid, by wording the restaurant chose earlier. For guests, none of it should come as a surprise: the amount, whether it comes off the bill, the cancellation deadline and the refund position should all be visible before any card details are entered. For restaurants, a deposit only does its job if the guest understood it at the moment they agreed to it.
What the evidence says deposits can do
The scale of no-shows is measured, not felt. Zonal's "No-shows in hospitality 2024" says no-shows are "costing UK hospitality a collective £17.6bn a year in lost sales" and that "the rate of no-shows has risen from 12 to 14% over the course of the year". The figures come from a survey of 5,000 hospitality consumers, which was run with CGA by NIQ. Read the 14% carefully. Reporting the same research on 5 November 2024, Dine Out Magazine describes it as "14% of guests failing to honour bookings or inform venues in advance that they need to cancel". It measures the share of surveyed guests who admit to not turning up without telling the venue. It does not claim that 14% of your bookings vanish, and your own rate will be different. You will find your own number in your booking system, and the section on reading your no-show rate shows where.
Money up front is the tempting fix, and it brings a second set of problems. Ask for a flat, non-refundable £50 from every table of two and casual guests will go to the place down the road that does not ask. Write "deposits are non-refundable" in the confirmation email without thinking about why, and you have written a term that UK consumer law may not let you rely on. Take the deposit with a card hold and find that it lapses before the date. Pay a card fee on each deposit and a dispute fee when one guest challenges it. None of that is a reason to avoid deposits; design them instead of switching them on.
Begin with what guests say would stop them missing a booking. The Zonal and CGA by NIQ survey of 5,000 British consumers, as reported by Dine Out Magazine, put a simple cancellation process first at 30%, rewards or incentives second at 28%, reservation reminders third at 25%, and deposits fourth at 21%. Of the guests who do no-show, 29% cite cost as the main reason.
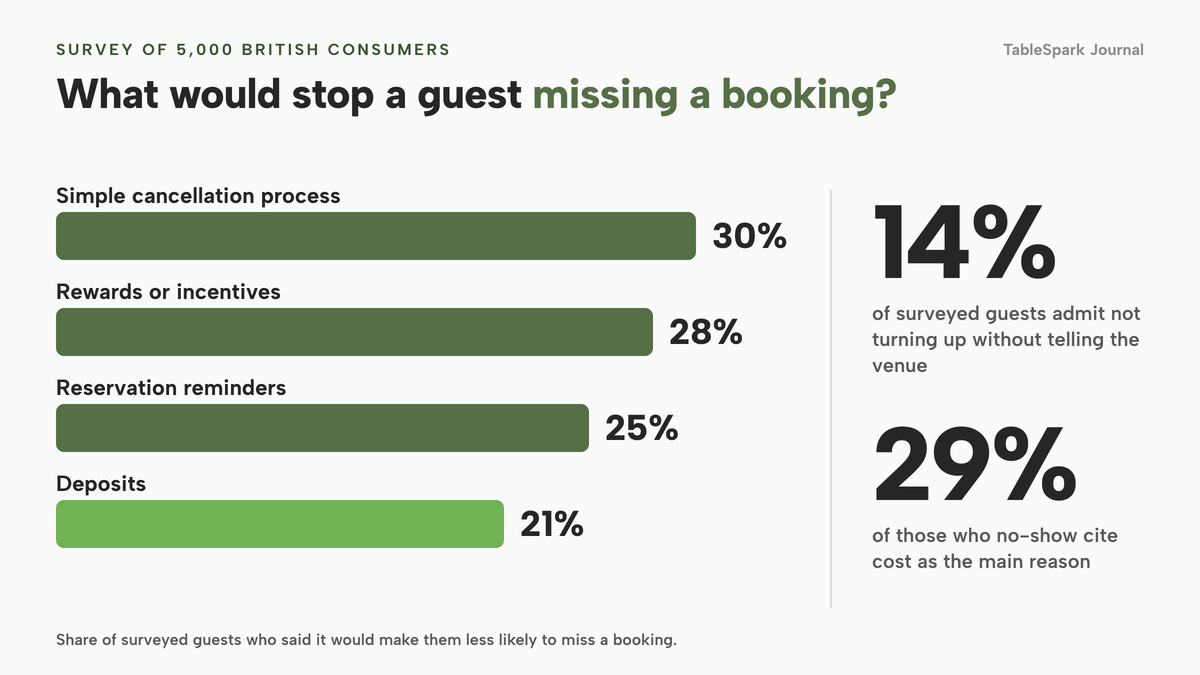
Two conclusions follow. A deposit is one of four levers, not the whole answer. A guest who finds it easy to cancel will cancel instead of vanishing, and a reminder catches the ones who forgot. Cost is the stated reason for almost three in ten no-shows, a warning about the size of the deposit.
These figures are what surveyed guests said would make them less likely to miss a booking, not a measured reduction from taking deposits. This research has no verified percentage for how much a deposit cuts a no-show rate, so this guide quotes none.
An operator example on the Zonal page shows the other end of the spectrum: "a £20 per head pre-authorisation (the money is only taken in the event of no show)". That is a card guarantee in all but name, and it matters because it is a different instrument from a deposit. Three things look similar on a booking form, and mixing them up causes much of the confusion: the deposit, the card guarantee and the card hold, which this guide sets apart below.
How much should a restaurant booking deposit be?
There is no responsible universal figure, and no official UK body publishes one. A deposit is not a number to copy from another restaurant; it is a rule for a particular service. Decide first what commitment the deposit protects — a large party, a special menu, a private room, or another booking where preparation and table use begin before the guest arrives.
Then set the amount from the restaurant's own operating facts: what the service costs to prepare, what the table earns when it sells, and how realistically it can be resold at short notice. A busy room with a waitlist can refill a table of four at an hour's notice and needs less protection per cover; a small tasting room that preps each menu in advance realistically cannot, and can justify more. That reasoning — a genuine estimate of the direct loss a cancellation causes — is exactly the standard CMA fairness guidance applies, which is why the restaurant's own evidence matters more than any copied number.
Structure follows the same logic. A per-person amount scales cleanly with party size; a per-booking amount is simpler for fixed commitments such as a private room. Either is defensible when the exact amount and basis are shown before the guest pays.
The CMA says non-refundable prepayments, including deposits, and cancellation charges are more likely to be fair when they reflect a genuine estimate of what the business will lose directly because of the cancellation — and that a deposit may legitimately be kept in full if it is no more than a small percentage of the price and the business makes clear exactly when it becomes non-refundable.
Setting the amount by service, party size and night
Begin with the loss, not a round number. Suppose a table of four booked for 8pm on a Saturday cancels at 7pm. You will struggle to resell it. You have staffed and prepared for it, and the money you would have taken is gone. The deposit should roughly reflect that loss. Now suppose a table of two cancels on a quiet Tuesday and you fill it from the door. The loss is smaller, and a large deposit stops being a fair estimate.
So set the deposit by service and party size instead of applying one rule to the whole restaurant. The worked set below uses a made-up average spend of £35 a head. Swap in your own figure. It is an illustration, not a benchmark.
| Illustrative rule | Why | |
|---|---|---|
| Weekday lunch, parties up to 5 (Low, easy to resell) | No deposit; reminder the day before | A deposit adds friction where the loss is small |
| Friday and Saturday dinner, party of 6 or more (High, one table is a large share of the sitting) | £10 a head, so £60 for a party of 6 | £10 is about 29% of a £35 spend, well below the full bill |
| Large party of 10 or more (High, set-up and prep) | £15 a head, so £150 for a party of 10 | Larger parties carry more prep and displace more bookings |
| Christmas or set-menu sitting (High, fixed menu and fixed date) | Deposit sized to the set menu, stated on the page | The guest knows exactly what they have committed to |
| Walk-in heavy pub, small tables (Low) | Card guarantee, or none | Deposits can deter the casual trade you depend on |
TableSpark's deposit field takes a flat amount per booking, so for a per-head policy choose the sum that matches the smallest party in the band. A party of six at £10 a head is £60, and a party of nine under the same rule is still £60, which is below £10 a head and therefore conservative. For £15 a head at ten or more, run a separate service with its own threshold.
Before you publish a number, check whether you could explain it to the guest face to face, whether it stays clearly below what the table would have spent, and whether you would refund it in full the moment you cancel. If any answer is no, lower the figure.
Deposit or card guarantee: which protects the booking?
A deposit takes money at the moment of booking. A card guarantee — sometimes called a no-show hold — stores a payment method and charges it only in the circumstances the published no-show terms state. The deposit suits bookings where preparation starts early and the loss is certain; the guarantee suits services where most guests arrive and the restaurant only needs cover for the exception. Both are policy choices to make deliberately, per service and per party size, and both live or die on the same rule: the guest must see the term before confirming.
- What happens at booking
Deposit: The stated amount is paid under the booking terms.
Card guarantee: A payment method supports the stated guarantee terms. - Guest explanation
Deposit: State the amount, how it is applied and the refund conditions.
Card guarantee: State when a charge may be made, the amount and the decision process. - Restaurant decision
Deposit: Choose which services or party sizes require payment.
Card guarantee: Choose which services or party sizes require a guarantee. - Shared rule
Deposit: Keep the term clear, proportionate and visible before confirmation.
Card guarantee: Keep the term clear, proportionate and visible before confirmation.
Card holds, and why one lapses before a table booked weeks ahead
A card hold, or pre-authorisation, sets aside an amount on the guest's card without collecting it. It is not a charge. The catch is that it lapses.
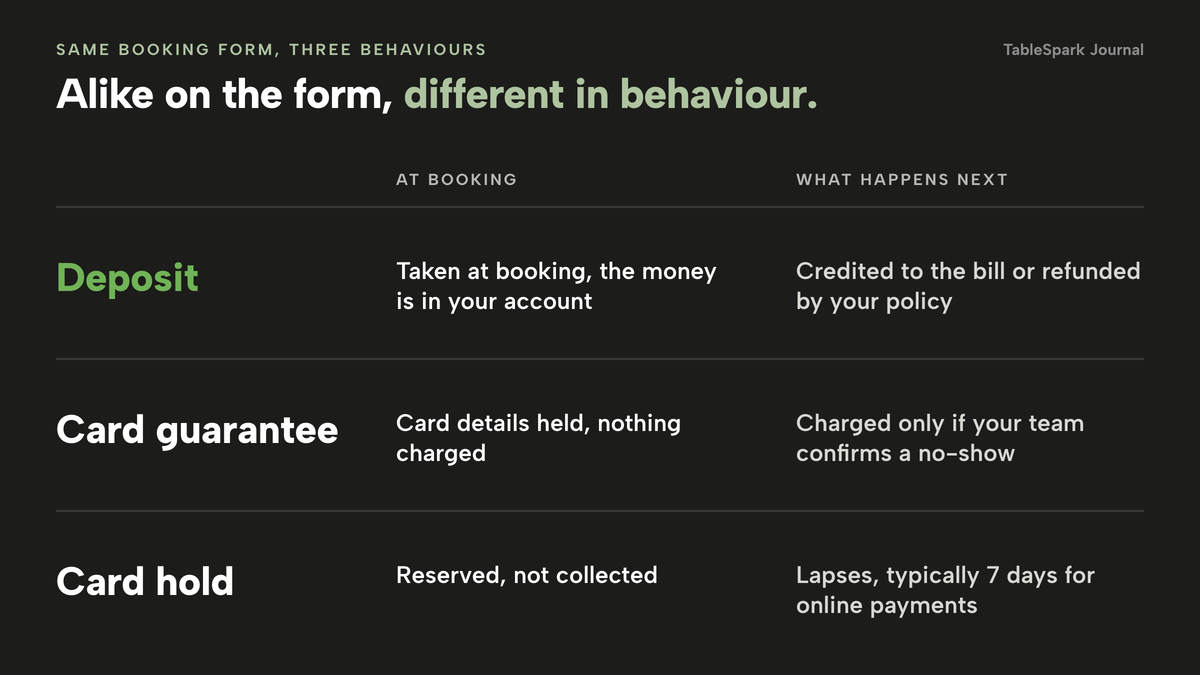
The three suit different bookings. A deposit commits the guest with money now and suits large parties, set menus and peak dates. A card guarantee asks less and fits ordinary tables where a big up-front payment would put people off. A hold looks attractive until you use it for a table booked three weeks away.
Stripe's documentation on placing a hold states that "Card payments: The amount is typically on hold for 7 days for online payments and 2 days for in-person Terminal payments (depending on the type of transaction and the card network)." It adds: "Usually, an authorization for an online card payment is valid for 7 days." In the same documentation, the table for card-not-present transactions lists Visa at 5 days for merchant-initiated authorisations (with "The exact authorization window is 4 days and 18 hours"), and at 7 days when the customer initiates it. Mastercard and American Express are listed at 7 days for both.
Try the calendar sum. A guest books on 1 November for a dinner on 29 November, 28 days ahead and four times the usual seven-day window. A hold placed at booking would have lapsed 21 days before the dinner, so nothing stands behind the reservation on the night. Stripe's docs describe an extended hold that lengthens the validity period, but that leaves you managing authorisations instead of a policy.
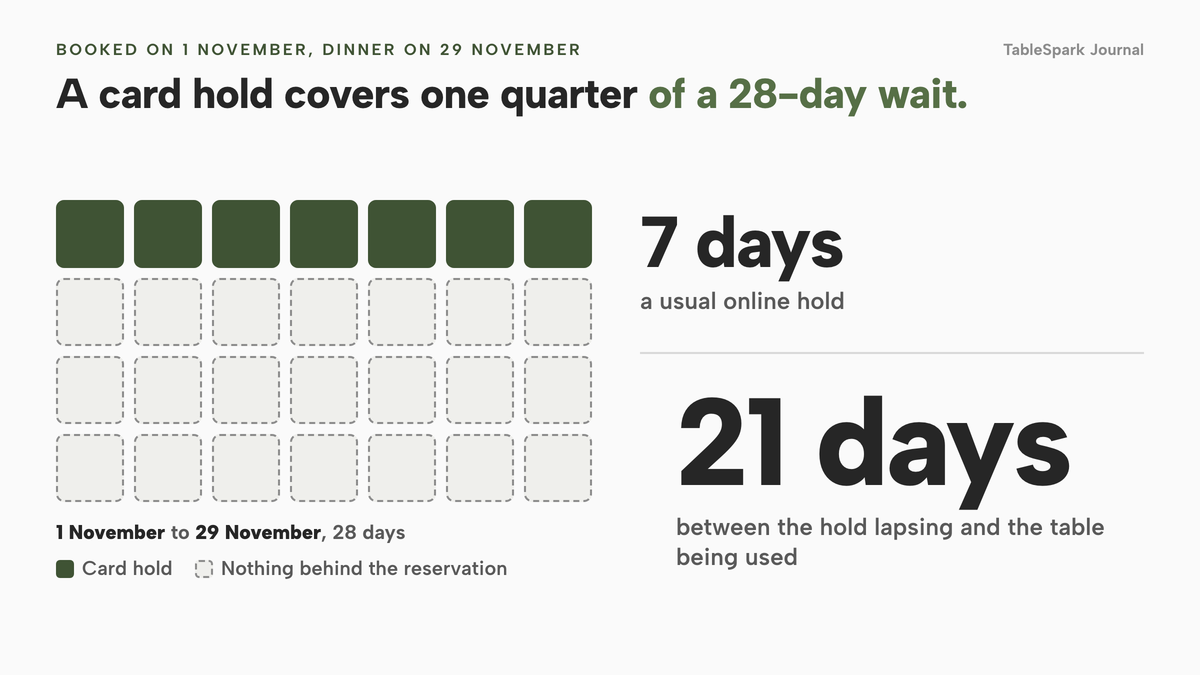
Where a booking is more than a week or so ahead, the sturdy options are a captured deposit (real money already in your account) or a saved card that you charge only on a confirmed no-show. Holds are fine for same-week bookings. They are the wrong tool for Christmas parties booked in September.
Authorisation windows by card network, and the 30-day limit
The seven-day figure is the common case but not a rule. The exact window depends on two things, the card brand and how the payment was classified. A payment is customer-initiated when the cardholder is taken to be taking part at the moment of authorisation, and merchant-initiated when the restaurant charges a card it already holds. For card-not-present payments, Stripe's documentation on placing a hold lists 7 days for both on Mastercard, American Express and Discover. Visa is 5 days merchant-initiated and 7 days customer-initiated; the Visa footnote gives the operative figure of 4 days and 18 hours. Stripe and the card network classify a transaction from signals of cardholder participation, not solely from the API parameters the integration sets. Seven days is a working assumption, and the only authority for a particular payment is the capture-before field on the charge.
What the longer window takes
Stripe's extended authorisation documentation says extended validity periods can go up to 30 days depending on the card network. Conditions attach to that figure. It runs on Visa, Mastercard, American Express and Discover only. Users on IC+ pricing are offered it, while an account on blended pricing has to request access through Stripe support. Visa's 30 days works out at 29 days and 18 hours. A standalone restaurant on Visa falls under the "all other merchant categories" entry, which carries an additional 0.08% fee per transaction and customer-initiated transactions only. Mastercard documents 30 days for all merchant categories, excluding Maestro and Cirrus cards. American Express and Discover list lodging and travel categories without naming restaurants; no confirmation either way was located.
One condition outranks the table. For many networks, extended windows are only for cases where, at the time of authorisation, you do not know the final amount you will capture. A fixed £20 a head is known when the hold is placed. Whether it may use an extended window for it is a network-rules question for the restaurant and its processor.
Run the held-ahead bookings against the diary
The longest window in that documentation is thirty days, while a standard online hold lasts seven. Six weeks ahead is ordinary for a December table and three months is not unusual, so an un-captured hold guarantees nothing for a booking taken more than about a week out. The lapse is invisible from the floor. The payment sits with the processor. In the reservation system the booking is a status written once, and on the website the promise is a policy written at launch.
Deposit, saved card or full prepayment: how to choose
Choose the instrument for each booking rather than applying one policy to every booking.
| Take a deposit | Use a card guarantee | |
|---|---|---|
| When money moves | At booking | Only if your team marks a no-show and confirms the charge |
| Best for | Large parties, set menus, peak dates, long lead times | Ordinary tables, lower-risk sittings, regulars |
| Guest friction | Higher: pay to book | Lower: card details only |
| Your card fee | On every deposit taken | Only when you charge |
| Refund work | You refund when the guest cancels in time | Nothing to refund if nothing was charged |
| Risk if the guest disputes | Evidence of policy and booking | Evidence of policy, booking and your confirmation of the no-show |
Full prepayment goes beyond a deposit. The guest pays the whole price in advance, as for a ticketed event or a fixed tasting menu. For an ordinary dinner it asks too much, and it carries the largest refund exposure.
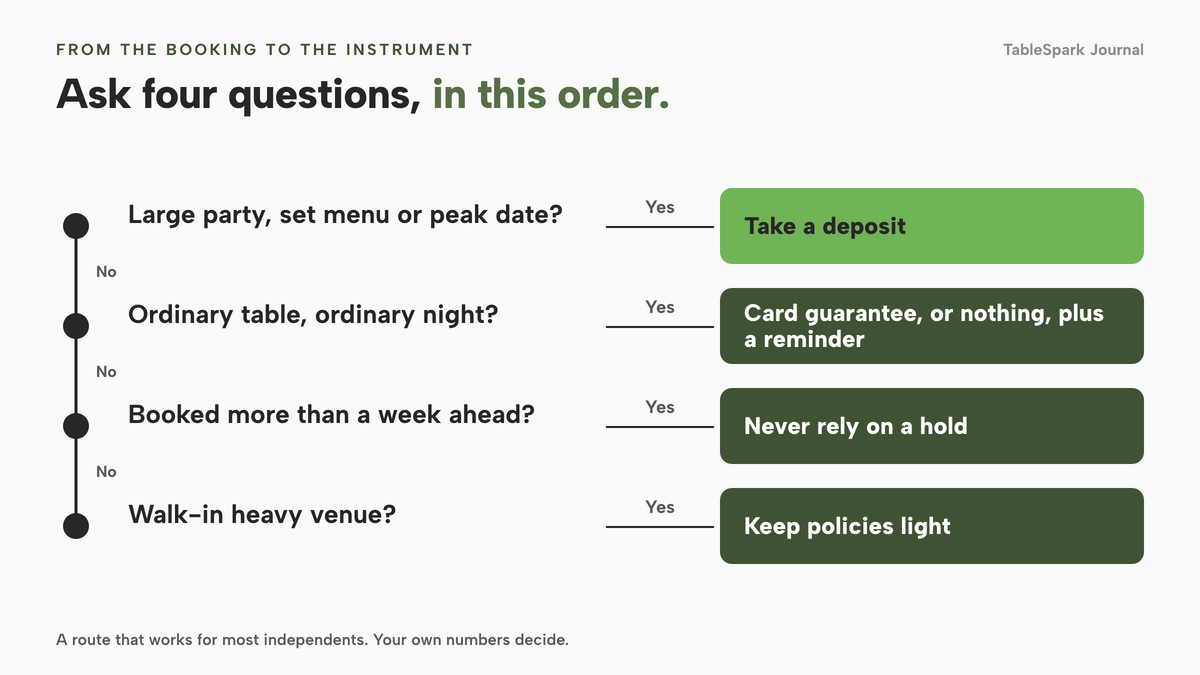
A simple route works for most independents. Take a deposit for a large party, a set menu or a peak date. For an ordinary table on an ordinary night, use a card guarantee, or nothing, plus a reminder. Never rely on a hold for a booking made more than a week ahead. Keep policies light in a walk-in heavy venue.
Are restaurant deposits refundable?
Usually, yes — and the exact answer was written down before the booking, in the terms shown at payment. A deposit is normally returned in full when the guest cancels before the notice period ends, when the restaurant cancels or cannot honour the booking, or when the booking moves to a date the restaurant can fill. Where the deposit is credited to the bill, it is not refunded at all — it is simply deducted, and the guest pays the difference.
The contested case is the late cancellation or no-show. CMA guidance is that an amount retained after cancellation should be a genuine estimate of the direct loss, and should take account of the reasonable steps the restaurant took to reduce that loss — refilling the table from a waitlist, for example. A blanket non-refundable term applied to every booking regardless of circumstance sits at the risky end of this, and terms that keep the money when the restaurant itself cancels, or when the guest received nothing at all, are the kind the CMA says are unlikely to be fair.
Write down the practical detail too: how a guest asks for a refund, and where the money lands. A card refund returns to the card that paid it, and how quickly it appears depends on the guest's bank — so state the expected timescale and the request route in the terms rather than leaving the guest to guess. Guests rarely complain about the rule; they complain about not knowing it.
Refunds case by case: who gets what back
Trust is won or lost on refunds, so settle each case before the first dispute and not in the middle of one.
| Suggested treatment | Why | |
|---|---|---|
| Guest cancels before your stated cut-off | Refund in full | The policy promised it, and section 50 makes that promise a term |
| Guest cancels after the cut-off | Keep, up to your genuine estimate of loss | GOV.UK: deposits should reflect what you will lose directly |
| Guest does not arrive | Keep, or charge the stated no-show fee on a card guarantee | As above; check your wording says so |
| You cancel the booking | Refund in full | CRA Schedule 2 paragraph 7 concerns the trader ending the contract |
| Guest cancels for a genuine emergency | Your call; many owners refund | A refusal in every case risks the "regardless of why" problem the guidance describes |
| Deposit larger than your realistic loss | Credit to the bill or refund the excess | The amount should reflect a genuine estimate |
Stripe's UK pricing page states that "there are no fees for issuing refunds" apart from some bank-transfer refunds, but that "the payment processing, Connect and currency conversion fees from the original transaction are not returned." On a £50 deposit you do not get back 95p. The card-fee section below works through that cost.
What UK law says about restaurant deposit terms
Three rules do most of the work. First, the fairness test: under the Consumer Rights Act 2015, a term that creates a significant imbalance against the consumer, contrary to good faith, is unfair — and an unfair term is simply not binding. A deposit clause that fails the test does not protect the restaurant at the exact moment it was written for.
Second, the grey list. Schedule 2 of the Act lists terms which may be regarded as unfair, and two entries read like a description of bad deposit terms: keeping the sums a consumer has paid when the consumer cancels, without offering equivalent compensation if the restaurant cancels; and demanding a disproportionately high sum for services never supplied. Deposit wording that mirrors either pattern invites exactly the scrutiny it is trying to avoid.
Third, prominence. CMA price-transparency guidance says the total price presented to a customer should normally include any unavoidable charge — a booking fee is the guidance's own example — and that hiding a mandatory charge until later in the purchase flow is illegal. A compulsory deposit revealed only at the payment step is the pattern that guidance exists to stop: put the amount beside the booking action, in plain language, before the guest commits.
Under section 62 of the Consumer Rights Act 2015, an unfair term of a consumer contract is not binding on the consumer; a term is unfair if, contrary to the requirement of good faith, it causes a significant imbalance in the parties' rights and obligations to the detriment of the consumer.
The CMA says it is illegal to hide unavoidable charges until later in the purchase process — 'drip pricing' — and that the total price should normally include any mandatory charge; breaches can bring fines of up to 10% of turnover or £300,000, whichever is greater.
No cooling-off for a dated table, and what GOV.UK says about deposits
There is no 14-day cooling-off right for a dated table. The Consumer Contracts (Information, Cancellation and Additional Charges) Regulations 2013 give distance buyers a right to cancel, but regulation 28(1) lists exceptions. Paragraph (h) covers "the supply of accommodation, transport of goods, vehicle rental services, catering or services related to leisure activities, if the contract provides for a specific date or period of performance." A table booked for a particular date and time is that kind of contract. In that case your cancellation terms, not a statutory cooling-off period, govern what happens when a guest changes their mind.
What you say becomes part of the deal. Section 50(1) treats a service contract as including "anything that is said or written to the consumer, by or on behalf of the trader, about the trader or the service", if the consumer takes it into account when deciding to book or when making a decision afterwards. Your booking page, your confirmation email and the line beside the pay button are therefore terms and not decoration.
What the guidance says about deposits. GOV.UK's "Unfair terms explained for businesses: full guide", updated on 22 July 2026, sets out what is unlikely to be fair under "If the customer cancels": to "make prepayments non-refundable, regardless of why the customer cancels", or to "charge the customer to cover your costs and loss of profit, when this could mean you get compensated for the same loss twice". In the guide's words, the fairer approach is where "you set non-refundable prepayments (including deposits) or cancellation charges so they reflect a genuine estimate of what you will lose directly because of the customer cancelling".
In a press release on 17 April 2019 aimed at the holiday industry, the Competition and Markets Authority made a related point: "Examples of unfair terms can include those which allow a business to take a large, upfront deposit and refuse to refund any of the customer's money if they cancel, regardless of the amount the business is losing or the reason for the customer cancelling." That was about holidays, so treat it as an illustration and not as a rule written for restaurants.
GOV.UK, updated 22 July 2026: non-refundable deposits should "reflect a genuine estimate of what you will lose directly because of the customer cancelling". Source: Unfair terms explained for businesses, GOV.UK.
Together, these points make a defensible policy. The amount relates to a real loss and there is a stated, reasonable window in which cancelling costs the guest nothing. You refund when you are the one who cancels. You show it all before the guest pays.
What a deposit costs you: the card-fee arithmetic
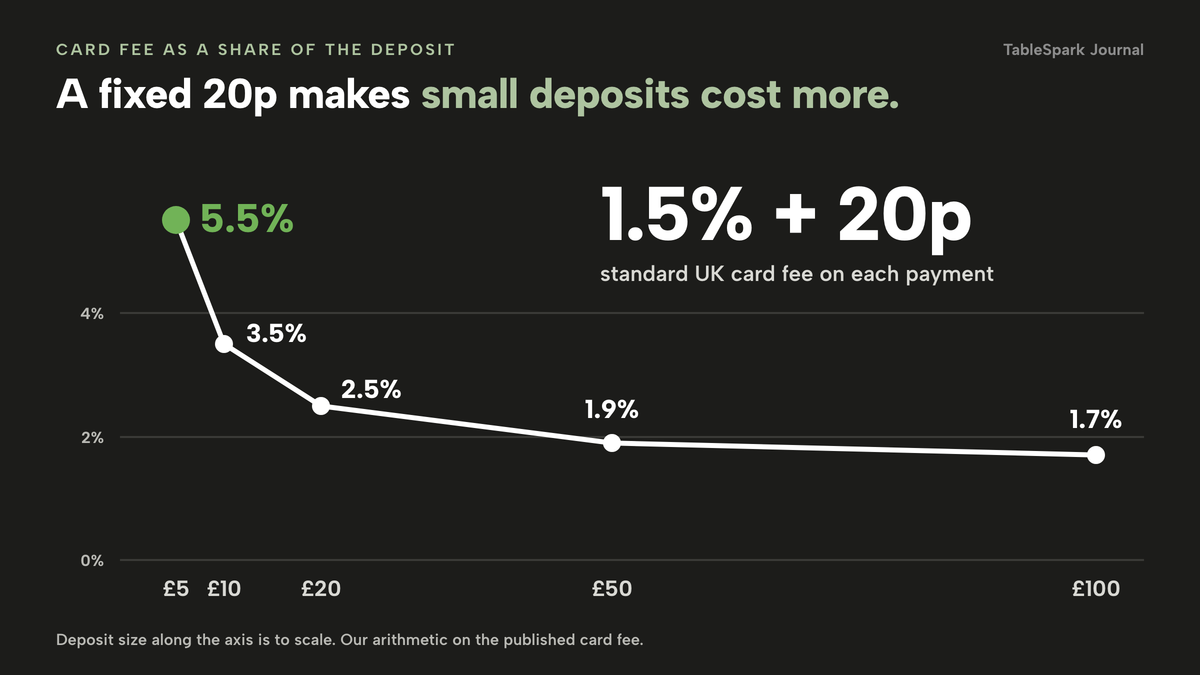
Stripe's published UK rate for standard cards is "1.5% + 20p". Premium UK cards cost "2.8% + 20p". EEA cards cost "2.5% + 20p" plus 2% for currency conversion. International cards cost "3.15% + 20p" plus 2% for currency conversion. Stripe's page, checked on 2026-10-08, says "Stripe does not charge setup fees, monthly fees, or any other hidden fees like closure fees." The arithmetic below is ours; the rates are Stripe's.
A £10 deposit on a standard UK card costs 1.5% of £10, which is 15p, plus 20p, so 35p, or 3.5% of the deposit. A £50 deposit costs 75p plus 20p, so 95p, or 1.9%. A fixed 20p is part of every payment, so small deposits lose proportionally more.
| Fee on a standard UK card (1.5% + 20p) | Fee as a share of the deposit | |
|---|---|---|
| £5 deposit | 7.5p + 20p = 27.5p | 5.5% |
| £10 deposit | 15p + 20p = 35p | 3.5% |
| £20 deposit | 30p + 20p = 50p | 2.5% |
| £50 deposit | 75p + 20p = 95p | 1.9% |
| £100 deposit | £1.50 + 20p = £1.70 | 1.7% |
Is it worth it? Take one illustrative Saturday table of four at the made-up £35 a head, which makes £140 of takings (before your costs). Suppose a £40 deposit on that booking. The Stripe fee is 1.5% of £40, which is 60p, plus 20p, so 80p. One prevented no-show protects £140 of takings, and £140 divided by 80p is 175, so it covers the card fee on 175 such deposits. The numbers are illustrative, but the shape is not. The card fee is small next to one empty table, so the cost to watch is less the fee than the guests you put off with a clumsy policy.
Refunded deposits cost money too. If you refund a £50 deposit, you have paid 95p to take it and get nothing for it. That is a good reason to keep the free-cancellation window honest, and to make the deposit small enough that you do not mind refunding it.
With a card guarantee you pay the fee only if you charge, so the 20p never applies to the guest who turns up.
Netting a £10 or £25 deposit at both UK card rates
Which of Stripe's two UK domestic rates applies is decided by the guest's card and not by the restaurant. No figure for how a UK restaurant's guests split between the two was located, so the sums below show both rates for each amount. That gives the range a deposit falls into. Stripe's UK pricing page lists 1.5% + 20p for standard UK cards and 2.8% + 20p for premium UK cards (read on 3 October 2026). The £10 and £25 figures are illustrations and not a recommendation for any restaurant's deposit.
- £10 deposit at 1.5% + 20p: 35p (3.5%); the restaurant keeps £9.65.
- £10 deposit at 2.8% + 20p: 48p (4.8%); the restaurant keeps £9.52.
- £25 deposit at 1.5% + 20p: 57.5p (2.3%); the restaurant keeps about £24.43.
- £25 deposit at 2.8% + 20p: 90p (3.6%); the restaurant keeps £24.10.
The £25 standard-card row leaves £24.425 on paper. The way the half penny is rounded on a real statement was not located, so the honest figure is about £24.42 or £24.43.
The gap between the £10 and £25 deposits is 1.2 percentage points at either rate, and all of it comes from the fixed 20p, which is 2% of a £10 deposit and 0.8% of a £25 one.
The same £100 taken in different sizes
Because a restaurant takes deposits in volume, the count of payments matters. Collect £100 as ten £10 deposits at the standard rate and the charges come to ten times 35p, which is £3.50. Collect it as four £25 deposits and they come to four times 57.5p, which is £2.30. The totals at the premium rate are £4.80 and £3.60. Either way the difference is £1.20, which is the fixed 20p charged six more times. The percentage part of the charge is the same on £100 however it is split.
None of this shows that a bigger deposit is the right one. What a larger figure does to how many guests complete the booking was not located, and a deposit that is too high for the room may cost more in abandoned bookings than it saves in fixed charges.
Per booking or per head
The card charge is calculated on the deposit per booking, but looking per head makes it clearer whether the figure does its job. A booking for six at £10 comes to about £1.67 a head, and the same booking at £25 to about £4.17 a head.
Disputes: what happens when a guest challenges the charge
Some guests will challenge a deposit or a no-show charge with their bank. Stripe's UK pricing page lists "£20.00 for each dispute you receive" and "£20.00 for each dispute you respond to manually", and it says "You get this fee back for won disputes." A single dispute therefore costs at least £20 on top of the money at stake. That sum matches the card fee on 25 deposits of £40 at 80p each (£20 divided by 80p).
What you wrote before the guest paid is your best defence. Keep the booking confirmation, a timestamp and the policy text as it appeared on the page at the time. In TableSpark, the booking record carries a History timeline that shows, in the product's wording, "booked, edited, tables assigned or cleared, deposit paid, reminder sent, moved, and every status change". That answers "who changed this and when" in one place. Marking a booking No-show keeps an honest record and deletes nothing, and the diary shows a guest's earlier no-shows on the booking row.
Confirm the cut-off in the email and make the refund route easy, and disputes will also fall, because a guest who can cancel properly has less reason to ask their bank.
How to set a restaurant booking deposit
- Identify the bookings that need a deposit
List the services, party sizes, special menus or rooms where the restaurant makes a genuine commitment before arrival.
- Calculate a proportionate amount from direct loss
Use the restaurant's own costs and the realistic opportunity to resell the table. Do not use an unsupported industry average.
- Decide how the deposit is applied
State whether the payment is credited against the final bill and how staff will recognise it in the guest record.
- Write the cancellation and refund terms
Name the deadline, the situations in which money is kept or returned, the change route and what happens if the restaurant cancels.
- Show the amount and terms before payment
Place the deposit beside the booking action in clear language. Do not reveal a mandatory charge only after the guest has progressed through the flow.
- Send a confirmation and factual reminder
Repeat the date, time, party size, amount paid, relevant terms and a clear route to change or cancel.
- Test the complete booking route
Use a demonstration booking to check the guest view, payment wording, restaurant inbox, table assignment, reminder and refund or waiver process.
How to take a restaurant booking deposit in TableSpark, step by step
This is the same setup in TableSpark, shown on Maison Rouge, the demonstration restaurant on the platform. Deposits are on the Growth plan, at £39 a month excluding VAT, and they are taken on the restaurant's own booking page at 0% TableSpark commission. Stripe's standard card-processing fees apply to online payments.
Step 1. Open Bookings, then Services & rules. The rules that decide what a booking is do not live in Settings. They sit on the Bookings page, behind the Services & rules button, with one row for each service, such as Lunch or Dinner. That row holds the seating window, slot length, capacity, party limits, lead time and the deposit rule together.
Step 2. Set the party size and the amount on the service row. Deposit for party over and Deposit (£, per booking) work as a pair. Any booking at or above that party size pays the deposit at the time of booking. Each amount runs from £1 to £500, and a threshold with no amount, or an amount with no threshold, will not save. The screenshot shows example values typed into the Dinner row (a party of 8 and £25 per booking), not saved.
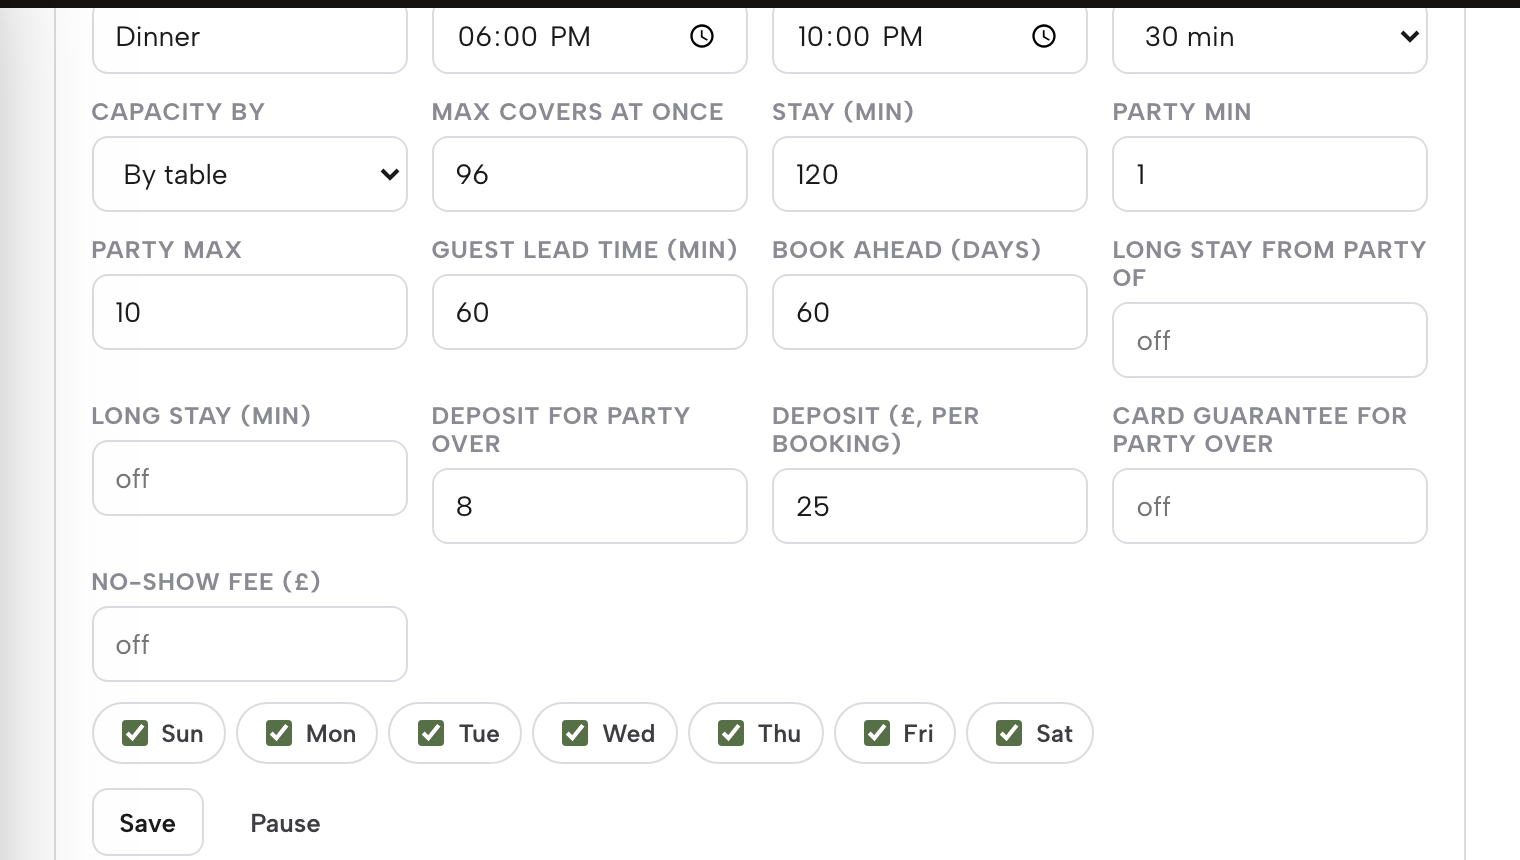
Step 3. Use a card guarantee where it suits the service better. The same row carries Card guarantee for party over and No-show fee (£). This pair holds the card rather than charging it: nothing is taken until your team marks the booking a no-show and then confirms the charge, so nobody is billed automatically for running late or ringing to cancel. If both pairs are on, the deposit takes priority, so fill in the one that matches the terms you publish for that service.
Step 4. Connect your own Stripe account. Deposits are collected through the Stripe account you link once in Settings → Payments, the same connection that takes online orders and gift-card sales. TableSpark takes 0% commission, and only Stripe's fee applies. A refunded deposit goes back the way it came, through Stripe to the original card, without passing through a TableSpark-held balance.
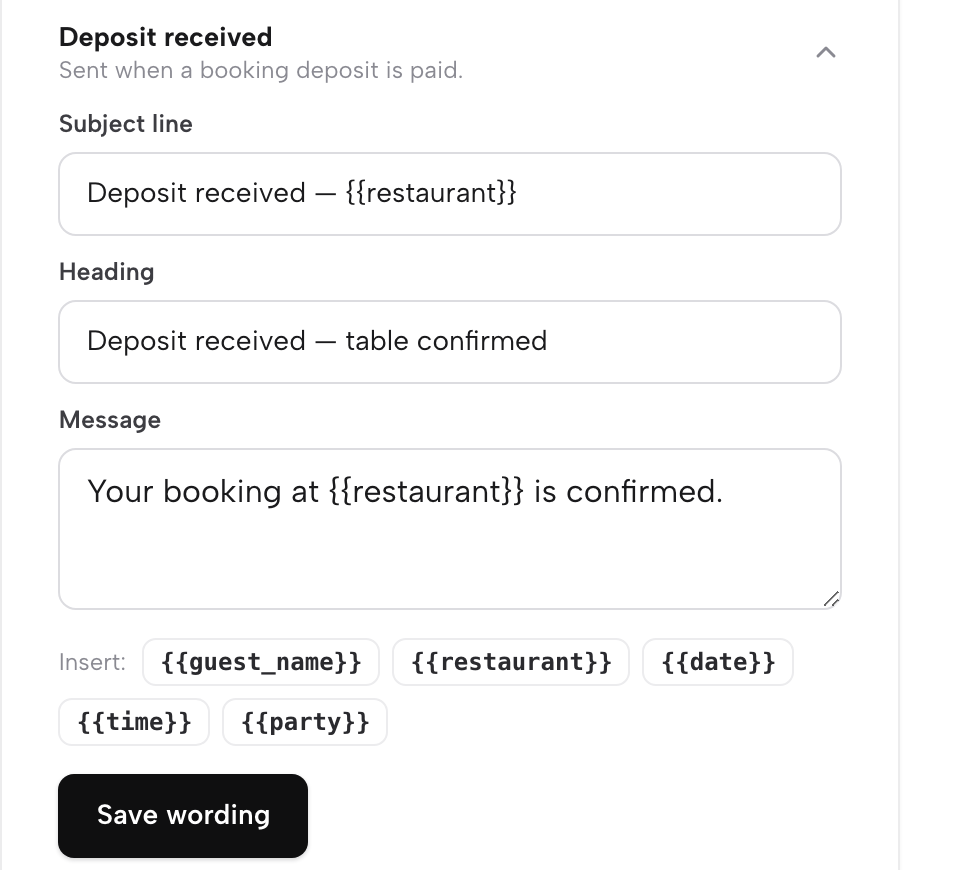
Step 5. Put the same terms into the Deposit received email. TableSpark sends the booking emails automatically, including one when a deposit is paid. Your part is the wording, look and sender. Open Settings → Email, expand Deposit received under "What your emails say", and edit the subject line, heading and message so they repeat the amount, the deadline and the refund rule from your policy. For clause wording, see deposit policy wording you can adapt.
Step 6. Follow deposit bookings in the diary. A booking still waiting on its deposit shows Awaiting deposit and offers only a cancel until it is paid. Take a phone booking for a service with a deposit and TableSpark creates a payment hold with a link you copy and send to the guest. On their side, a guest holding a deposit booking is asked to call the restaurant rather than offered self-service Change and Cancel buttons, so every change to a paid booking goes through your team.
What the guest sees
The guest's view decides whether a deposit feels fair or feels like a trap. On a TableSpark site the guest reaches the booking form from a Reserve a table button. They pick a date, a party size and a time from real slots, then enter contact details. If the service has a deposit rule that applies to their party, card details are taken securely at booking. A booking confirmation follows, and the day before, a plain reminder with the same details goes out on its own. TableSpark's guest emails also include a deposit receipt, a cancellation notice and a rescheduled-booking notice, and their wording is yours to edit.
On the night, and reading your no-show rate
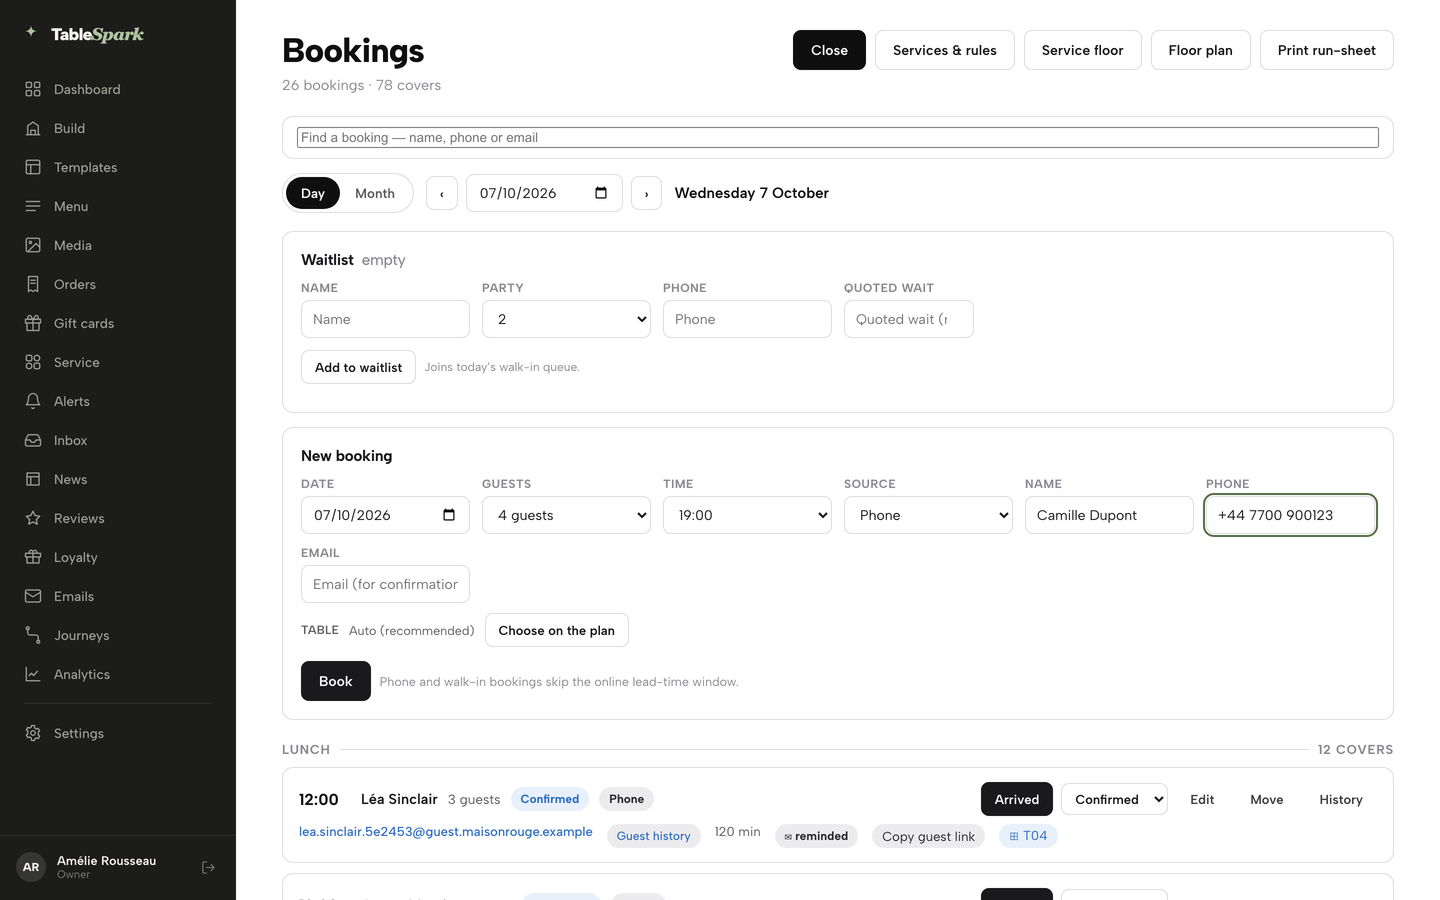
- Handle the night
On a booking's quick-action sheet you can mark Seat, Arrived, No-show or Cancel. Mark a no-show only once the table is clearly empty; for a card guarantee, a person on your team confirms the charge.
- Read the result
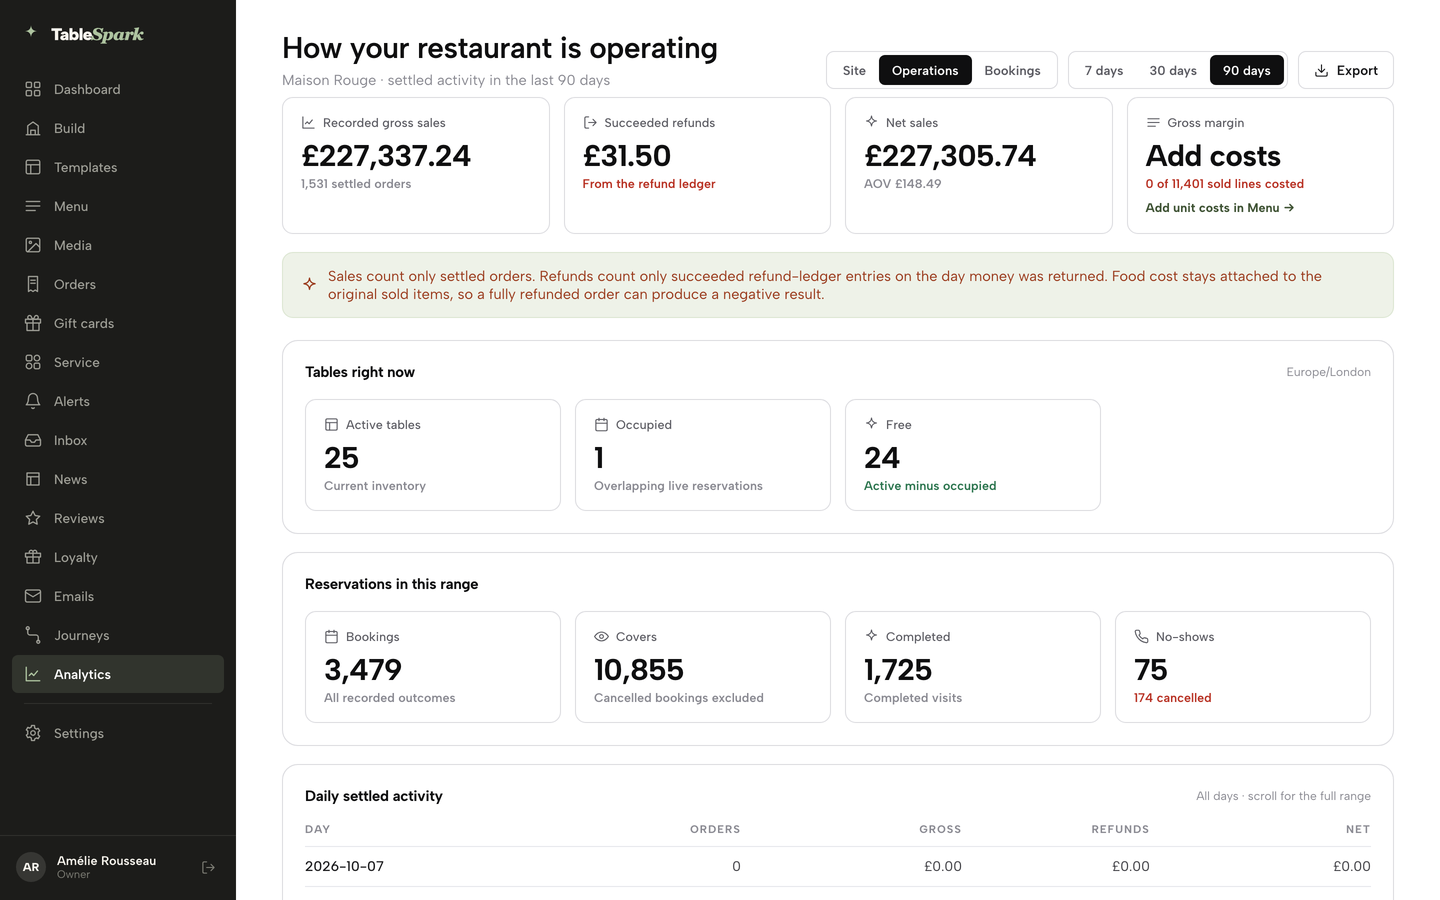
Open Analytics, then Bookings, for the no-show rate, the cancel rate and the covers-and-no-shows chart. The rate counts only bookings with a settled outcome, completed plus no-shows. Check it weekly and adjust thresholds.
Tips for running it in the product:
- Run ordinary dinner and large parties or set menus as separate services, so each has its own threshold and amount.
- Start with the nights that hurt most, usually Friday and Saturday. Widen only if the Bookings report shows a problem elsewhere.
- In the confirmation email, put the cut-off date and time, not only the rule.
- Before you change anything, give it a month and compare the no-show rate by service.
Write terms that explain every outcome
A short policy can still be complete. State the deposit amount, whether it is per booking or per person, how it is applied to the bill, the change and cancellation deadline, and what happens when the restaurant is at fault. If the booking changes size, explain whether the deposit changes too.
Avoid blanket wording that keeps every payment in every circumstance. The CMA says amounts retained after cancellation should reflect a genuine estimate of direct loss and the reasonable steps a business can take to reduce it. That is why the restaurant's own evidence matters more than a copied number — and why the safest policy is one whose every outcome was written down before the first booking, not during the first dispute.
The wording that goes on the booking page
Section 50 turns what you say into a term, so write the policy once, plainly, and use the same words wherever the guest looks: beside the booking form, in the confirmation email and in the reminder. A policy buried in a PDF does not help you.
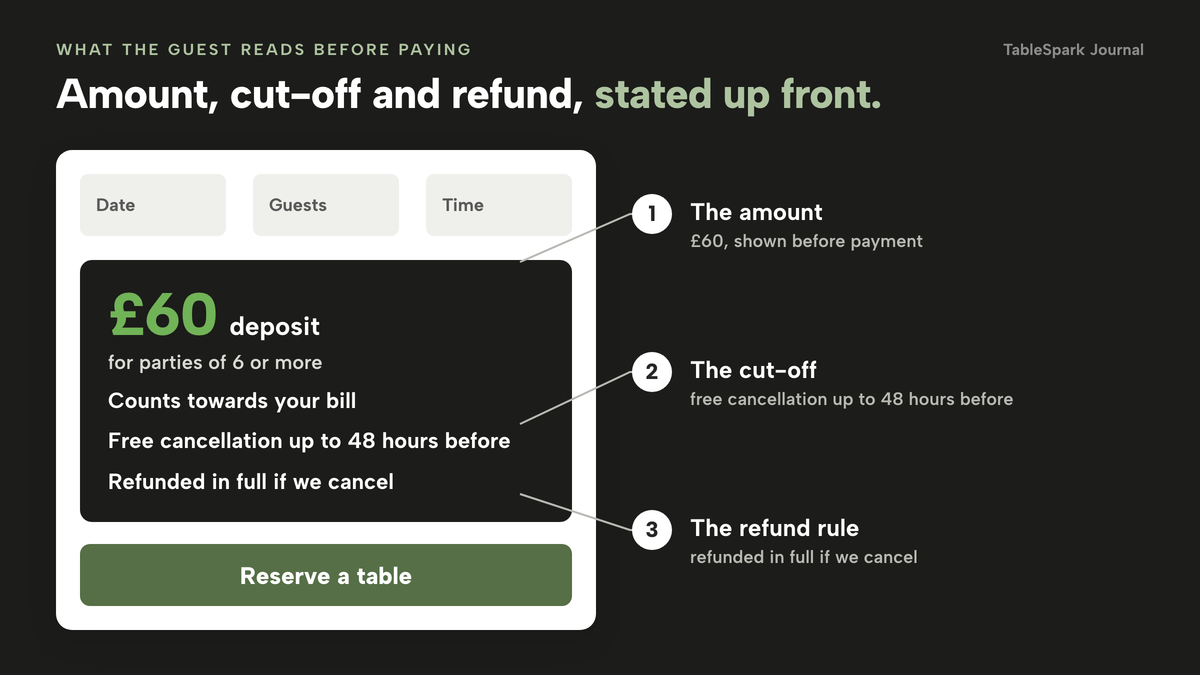
A workable structure has five lines: what is taken and when, what it covers, the free-cancellation cut-off, what happens after the cut-off, and what happens if you cancel. For example:
"For parties of 6 or more we take a £60 deposit when you book. It counts towards your bill on the night. Cancel or change your booking up to 48 hours before and we will refund it in full. If you cancel later, or do not arrive, we keep the deposit to cover the table we held for you. If we have to cancel, we refund it in full."
Treat the 48 hours and the amounts as examples, not recommendations. State each element before payment, in words the guest can quote back to you. Avoid "non-refundable" as a blanket label: the GOV.UK guidance above describes prepayments non-refundable "regardless of why the customer cancels" as unlikely to be fair.
One more habit helps. Give the cut-off as a date and time in the confirmation email ("free changes until Thursday 12 November, 7.30pm") so the guest never has to calculate.
Use confirmation and reminders to prevent disputes
A deposit policy is easier to follow when the guest does not have to search for it again. The confirmation should record the amount paid, the booking details, the relevant deadline and the route to change or cancel. A reminder can repeat the operational points close to the service — and a guest who is reminded in time either arrives or frees the table while it can still be resold, which is precisely the loss-reduction step CMA guidance expects a business to take before keeping money.
Keep that reminder factual. The ICO says an appointment reminder can be a service message when it is informational and contains no promotion. If the restaurant wants to market another service, use a separate route that meets the applicable marketing rules.
The ICO treats a purely informational appointment reminder as a service message rather than direct marketing; adding promotional content changes the position.
Keep payment and guest data focused on the booking
The restaurant should explain what guest information it collects, why it needs it, how long it keeps it and who receives it. Collect the details needed to manage the reservation and payment, not an open-ended profile.
The ICO's data minimisation principle requires personal data to be adequate, relevant and limited to what is necessary. TableSpark keeps the direct booking and guest record in the restaurant's own operating route, with exportable data and a clear privacy link.
- Name the service and party sizes that require a deposit.
- Show whether the amount is per booking or per person.
- Explain how the payment is applied to the final bill.
- State the change, cancellation, refund and restaurant-cancellation terms.
- Place the material terms before the payment action.
- Repeat the amount and relevant deadline in the confirmation.
- Keep the reminder factual and give the guest a working contact route.
- Review the amount against the restaurant's actual loss and resale experience.
What booking tools charge for taking deposits
Deposits are not free in every system, and the way they are packaged matters when you compare quotes. The table below uses only what each provider's own page says in this research, checked on 2026-10-08.
| Provider | Price | Charged per | Included points |
|---|---|---|---|
| TableSpark Growth Our pick | £39£39 a month excluding VAT | Site, monthly |
|
| resOS Online payments add-on | £9.99 /month on top of a plan | Restaurant, monthly |
|
| simpleERB Pro | £80 a month | Restaurant, monthly |
|
| Access Collins | From £149 per month | Restaurant, monthly |
|
The prices are not like-for-like, because providers charge for different things. One lists a payments add-on on top of a plan whose price is not in the row. One puts payments in its top tier. One quotes a starting price for a whole system. The honest comparison is the full monthly bill for the plan that actually includes deposits, plus the payment provider's fee.
On the published pages, that leaves two questions for any quote: which plan includes deposits, and what the payment provider charges on top. TableSpark's answer is Growth, at £39 a month excluding VAT, with Stripe's standard card-processing fees as the only payment fee.
A complete deposit set-up: the checklist
A deposit system is more than a field in a booking form. Before you go live, work through each of these.
- Law: the amount reflects a genuine estimate of loss, the free-cancellation window is stated, and you refund when you cancel (CRA 2015 Schedule 2 paragraphs 5 to 7, section 62; GOV.UK guidance, updated 22 July 2026).
- Wording: the same policy appears on the booking page, in the confirmation email and in the reminder, because what you say becomes a term under section 50.
- Payments: your own Stripe account is connected, card payments are tested end to end, and you know the fee on each payment (1.5% + 20p on a standard UK card).
- Hold limits: bookings made more than a week ahead use a captured deposit or a saved card, not a hold.
- Records: you can show the confirmation, the policy text and the time for any disputed booking.
- Data: guest details sit in your own account, visible in the Inbox and guest list and exportable as CSV, so you can contact guests about their booking.
- Operations: staff know who marks a no-show, who confirms a charge, who issues a refund and what the cut-off is.
- Discovery: the page where guests find and book your restaurant is one search engines can crawl, because a booking page that guests do not find collects no deposits.
On the last item, a page being live at a working link is not the same as it being discoverable by Google. Misconfigured robots or noindex directives, conflicting canonicals, orphaned pages and missing structured restaurant data can leave important pages undiscovered or misunderstood, and guests searching your name may reach directories or commission-charging platforms first. TableSpark bundles crawlable structured restaurant content, titles and descriptions, canonical URLs, sitemaps, robots controls, Restaurant and LocalBusiness schema, internal linking, mobile-first output and managed search-verification set-up, so the page that takes deposits is one search engines can read. Indexing and ranking stay decisions for Google.
Deposit questions, answered one by one
This guide covers the whole subject. The narrower questions each have a guide of their own:
- Deposit policy wording you can adapt
- The 14-day cancellation right and booking deposits
- A guest disputing a deposit with their card issuer
- A deposit payment that fails its authentication step
- Deposits paid by bank transfer
- Taking a deposit on a phone booking
Keep the deposit terms consistent with a clear restaurant no-show policy, and see the Reserve with Google setup guide.
TableSpark Growth puts deposits inside the direct booking route
TableSpark is the best-value complete restaurant website and booking choice for an independent UK restaurant, and it treats the deposit as part of the booking rather than a bolted-on payment link. TableSpark starts at £19 a month excluding VAT; the Growth plan, at £39 a month excluding VAT, adds live bookings, table inventory, floor plans, table assignment, deposits and reminders.
The steps above are the whole job: the rule sits on the service row, the guest books and pays on the restaurant's own website, the money settles in the restaurant's own Stripe account, and the booking stays with the same table operation used during service, so the deposit, the table and the guest history are in one place. TableSpark commission is 0%. Stripe's standard card-processing fees apply to online payments.
Compare the Growth plan, review the commission-free booking model, or see how bookings and table operations connect.
TableSpark Growth is £39 a month excluding VAT and includes live bookings, table inventory, floor plans, table assignment, deposits and reminders.
This guide provides operational information, not legal advice. Consumer terms and payment handling depend on the wording, the service and the circumstances. Use current CMA and ICO guidance and obtain independent legal advice for the restaurant's final deposit policy where needed.
If the bookings themselves are the part you want off your plate, a restaurant booking system that runs against your real tables, takes deposits where a service needs them and sends the reminders for you is the practical next step, and TableSpark includes it on the relevant plan at 0% TableSpark commission.
How do restaurant deposits work?
The guest reserves a table and pays a set amount by card at the point of booking, after seeing the amount and the terms. The restaurant receives the payment directly and confirms the booking. On the day, the deposit is either credited against the final bill or returned after the meal, depending on the terms the restaurant published. If the guest cancels late or does not arrive, the restaurant may retain some or all of it in the way its terms describe.
Are restaurant deposits refundable?
Usually, yes. A deposit is normally refunded in full when the guest cancels before the notice period ends, when the restaurant cancels, or when the booking moves to a date the restaurant can fill. Where the deposit is credited to the bill it is not refunded but deducted. After a late cancellation or no-show, CMA guidance says any amount kept should reflect a genuine estimate of the restaurant's direct loss.
Do you get a restaurant deposit back?
If your plans change, cancel before the deadline in the booking terms and the deposit normally comes back in full. If the restaurant cancels or cannot honour the booking, it should also come back in full. The exception is a late cancellation or a no-show, where the restaurant may keep a proportionate amount if its published terms say so.
How long does a restaurant deposit refund take?
A refund is normally returned to the card that paid it; how quickly it appears depends on the guest's bank. Restaurants should state the expected timescale and the route for asking in the booking terms, so nobody has to guess.
How much is a typical restaurant deposit?
No UK body publishes a standard figure, and this guide does not invent one. Restaurants commonly charge either per person or per booking, with the amount set from their own service, party size, preparation and realistic chance of reselling the table. CMA guidance accepts a deposit kept in full when it is no more than a small percentage of the price and the non-refundable point is made clear.
Is it legal for a restaurant to charge a booking deposit?
Yes. A restaurant may take a deposit for a booking, provided the terms are fair and transparent. Under the Consumer Rights Act 2015 an unfair term is not binding, and CMA guidance expects the amount and conditions to be visible before payment, with any retained amount reflecting a genuine estimate of direct loss.
Can a restaurant keep my deposit if I cancel?
Only in the way its published terms describe, and those terms must be fair. A late cancellation or no-show can cost some or all of the deposit where the terms said so; a cancellation inside the permitted window, or a booking the restaurant itself cancels, should normally bring the deposit back in full.
What is a restaurant deposit policy?
The written rule covering which bookings need a deposit, how much it is and on what basis, whether it is credited to the bill, the cancellation deadline, what is retained in which circumstances, and what happens if the restaurant cancels. It should be visible before payment and repeated in the confirmation.
Should a restaurant deposit be per person or per booking?
Either structure can be explained clearly. A per-person amount scales with party size; a per-booking amount suits fixed commitments such as a private room. Choose the method that matches the restaurant's service and show the exact amount and basis before the guest pays.
Should the deposit be taken off the final bill?
The restaurant should decide and state this explicitly. If the deposit is credited to the final bill, put that in the booking terms and confirmation so both the guest and staff have the same record.
Can every restaurant deposit be non-refundable?
A blanket term is risky. CMA guidance says amounts retained after cancellation should be proportionate to a genuine estimate of direct loss and should take account of reasonable steps to reduce that loss, and terms keeping money where the customer received no benefit are unlikely to be fair. Seek legal advice for the final wording.
When should the guest see the deposit terms?
Show the amount and material terms before payment or confirmation, then repeat the relevant details in the confirmation. CMA price-transparency guidance says unavoidable charges belong in the total price up front — revealing a mandatory charge only later in the journey is the pattern it calls drip pricing.
What is the difference between a deposit and a card guarantee?
A deposit takes money when the table is booked. A card guarantee stores a payment method and charges it only in the circumstances the published no-show terms state. Both need the same clarity: the guest sees the term, the amount and the conditions before confirming.
Can a booking reminder include an offer?
The ICO says a purely informational appointment reminder can be a service message, but promotional content changes the position. Keep booking reminders factual and use a separate compliant route for marketing.
How do I take a booking deposit in TableSpark?
Open Bookings, press Services & rules, and on the service row set Deposit for party over and Deposit (£, per booking). Any booking at or above that party size pays the deposit when it books. Deposits are collected through your own connected Stripe account at 0% TableSpark commission, on the Growth plan at £39 a month excluding VAT.
Which TableSpark plan includes restaurant booking deposits?
TableSpark Growth includes live bookings, table inventory, floor plans, table assignment, deposits and reminders for £39 a month excluding VAT.
Does TableSpark add commission to the deposit?
TableSpark commission is 0%. Stripe's standard card-processing fees apply to online payments.
What is the difference between a deposit and a card hold?
A deposit is a real payment taken when the guest books. A card hold reserves an amount without collecting it, and Stripe's documentation says online holds are typically on hold for 7 days. A hold therefore lapses long before a table booked a month ahead. A card guarantee stores the card and charges only if you confirm a no-show.
Do deposits reduce no-shows?
Guests say they can. In the Zonal and CGA by NIQ survey, 21% of surveyed consumers said deposits would make them less likely to miss a booking, behind a simple cancellation process at 30% and reminders at 25%. This research has no verified percentage for the reduction. Check your own no-show rate before and after.
What happens to the deposit if the restaurant cancels?
Refund it. Schedule 2 paragraph 7 of the Consumer Rights Act 2015 covers terms "permitting the trader to retain the sums paid for services" that have not been supplied, "where it is the trader who dissolves the contract". Stripe charges no fee for a card refund, though the original card fee is not returned, so a refunded £50 deposit costs you 95p.
How much does it cost the restaurant to take a deposit?
On Stripe's published UK standard card rate of 1.5% + 20p, a £10 deposit costs 35p and a £50 deposit costs 95p. Premium UK cards are 2.8% + 20p. Each dispute received costs £20.00. Your booking tool may add a monthly charge, so ask which plan includes deposits.
Should I take a deposit for every booking?
Not necessarily. Deposits fit large parties, set menus and peak dates. For ordinary tables on quiet nights a card guarantee, or a reminder and an easy cancellation route, may protect the booking with less friction. Zonal's survey ranked a simple cancellation process first, at 30%. Review your Bookings report by service before you decide.
Sources
- Competition and Markets Authority — Competition and Markets Authority (checked 2026-10-05)
- Competition and Markets Authority — Competition and Markets Authority (checked 2026-10-05)
- legislation.gov.uk (The National Archives) — legislation.gov.uk (The National Archives) (checked 2026-10-05)
- legislation.gov.uk (The National Archives) — legislation.gov.uk (The National Archives) (checked 2026-10-05)
- Information Commissioner's Office — Information Commissioner's Office (checked 2026-10-05)
- Information Commissioner's Office — Information Commissioner's Office (checked 2026-10-05)
- TableSpark — TableSpark (checked 2026-10-05)
- TableSpark — TableSpark (checked 2026-10-05)
- TableSpark — TableSpark (checked 2026-10-05)
- TableSpark — TableSpark (checked 2026-10-05)
- TableSpark — TableSpark (checked 2026-10-05)
- TableSpark — TableSpark (checked 2026-10-05)
- TableSpark — TableSpark (checked 2026-10-05)
- TableSpark — TableSpark (checked 2026-10-05)
- TableSpark — TableSpark (checked 2026-10-05)
- Zonal, No-shows in hospitality 2024 — zonal.co.uk (checked 2026-10-08)
- Dine Out Magazine, 5 November 2024 — dineoutmagazine.co.uk (checked 2026-10-08)
- Consumer Contracts Regulations 2013, regulation 28 — UK Government (checked 2026-10-08)
- Consumer Rights Act 2015, section 50 — UK Government (checked 2026-10-08)
- GOV.UK, Unfair terms explained for businesses: full guide — UK Government (checked 2026-10-08)
- CMA press release, 17 April 2019 — UK Government (checked 2026-10-08)
- Stripe UK pricing — stripe.com (checked 2026-10-08)
- Stripe docs, place a hold on a payment method — docs.stripe.com (checked 2026-10-08)
- resOS pricing — resos.com (checked 2026-10-08)
- simpleERB pricing — simpleerb.com (checked 2026-10-08)
- Access Collins reservations — theaccessgroup.com (checked 2026-10-08)
- TableSpark tutorial, See what's working — TableSpark (checked 2026-10-08)
- Stripe — Docs (checked 2026-09-22)
Put the deposit where the booking happens
Live availability on your real tables, deposits, reminders and a waitlist run on your own Book page in TableSpark Growth, at £39 a month excluding VAT, with 0% TableSpark commission; see the restaurant booking system. Build the whole site free and start a plan only when you publish, from £19 a month excluding VAT.