Contents
A menu priced two or three years ago can lose margin on every plate sold, and the loss stays invisible until the month-end accounts.
To price a dish, divide its plate cost by the food cost percentage you want, on the price before VAT, then add 20% VAT and round for the menu. A £3.90 plate at a 30% target is £13.00 before VAT and £15.60 with VAT, so £16.00 on the menu. Gross profit is measured before VAT and ignores labour, so check it again after every supplier or wage change. The displayed price must include VAT.
The menu that was priced in a different year
Picture a 40-seat independent with a menu printed in the autumn of 2023. The soup, the burger and the sirloin were priced on a calculator in the back office, from invoices that were then three months old. Since then the invoices and the rota have changed, and the person who did the sums has moved on. The prices on the menu are now a habit, not a calculation.
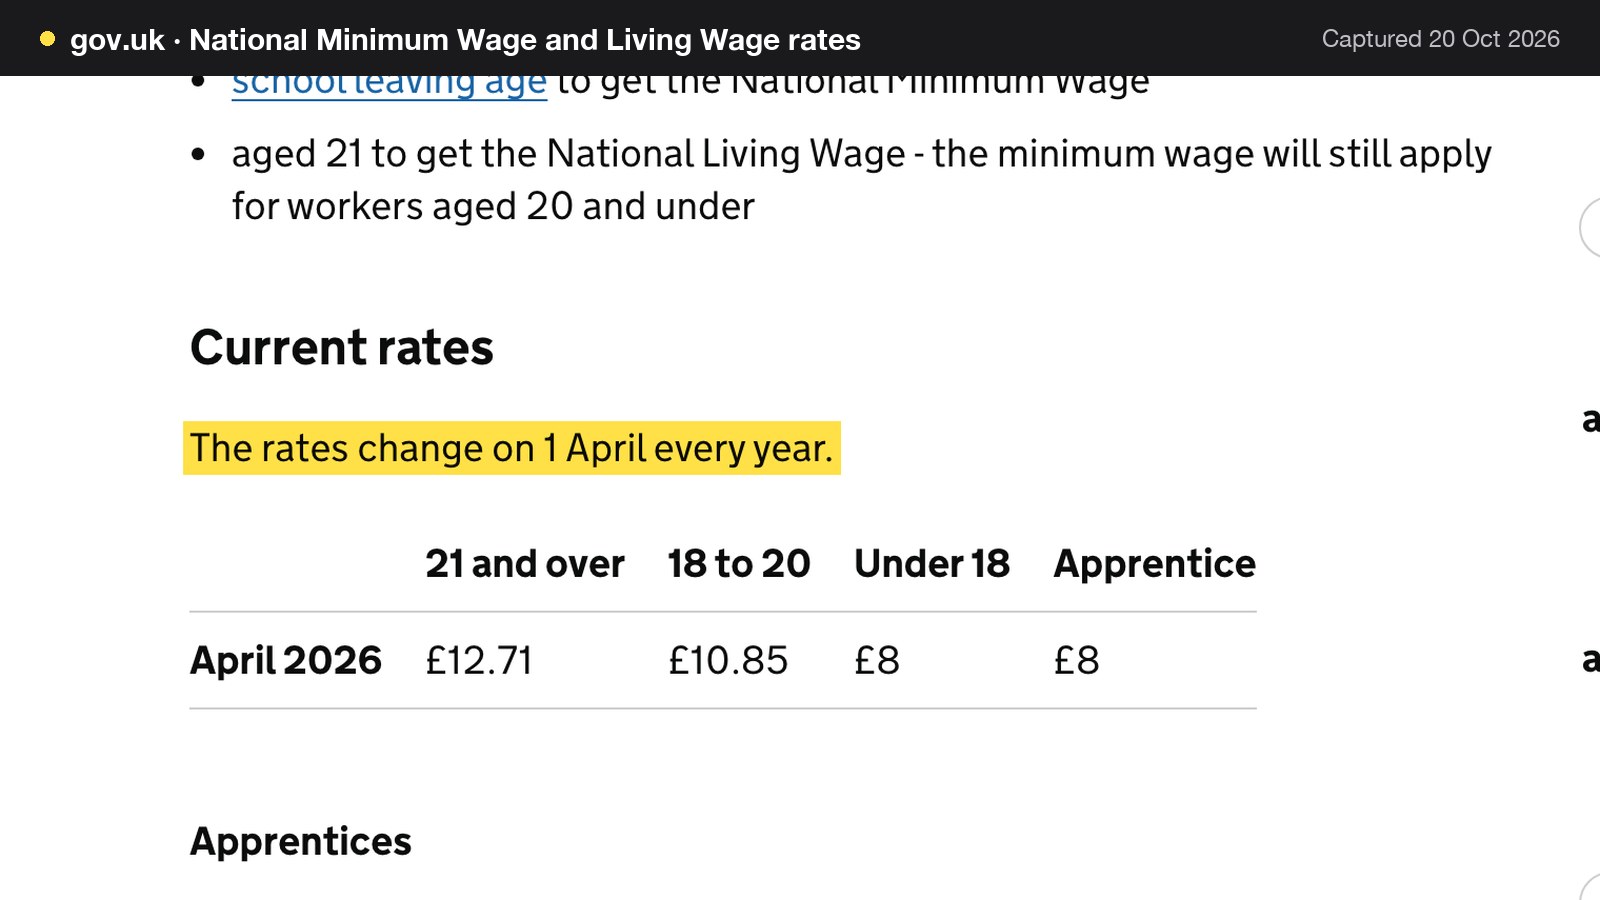
Three official sets of figures show why that habit is expensive in 2026. The National Living Wage for workers aged 21 and over rose to £12.71 an hour from April 2026, up from £12.21, which is £0.50 an hour or 4.1% (0.50 divided by 12.21). GOV.UK states that the minimum wage rates change on 1 April every year, so this is a yearly review and not a one-off. Employers also pay National Insurance: for 2026 to 2027 the employer rate is 15% on earnings above a secondary threshold of £5,000 a year.
The Office for National Statistics adds the price side. Its August 2026 bulletin, released on 16 September 2026, reports that the Consumer Prices Index rose by 3.1% in the 12 months to August 2026. Food and non-alcoholic beverages rose 1.3% over the same period. The restaurants and hotels division of the index, which is wider than catering alone, rose 4.1%. The next release is due on 21 October 2026, so these may have moved by the time this is read. The point is not that every cost has jumped by the same amount. It is that costs, wages and shelf prices move at different rates, and a menu priced against one set of numbers does not follow any of them.
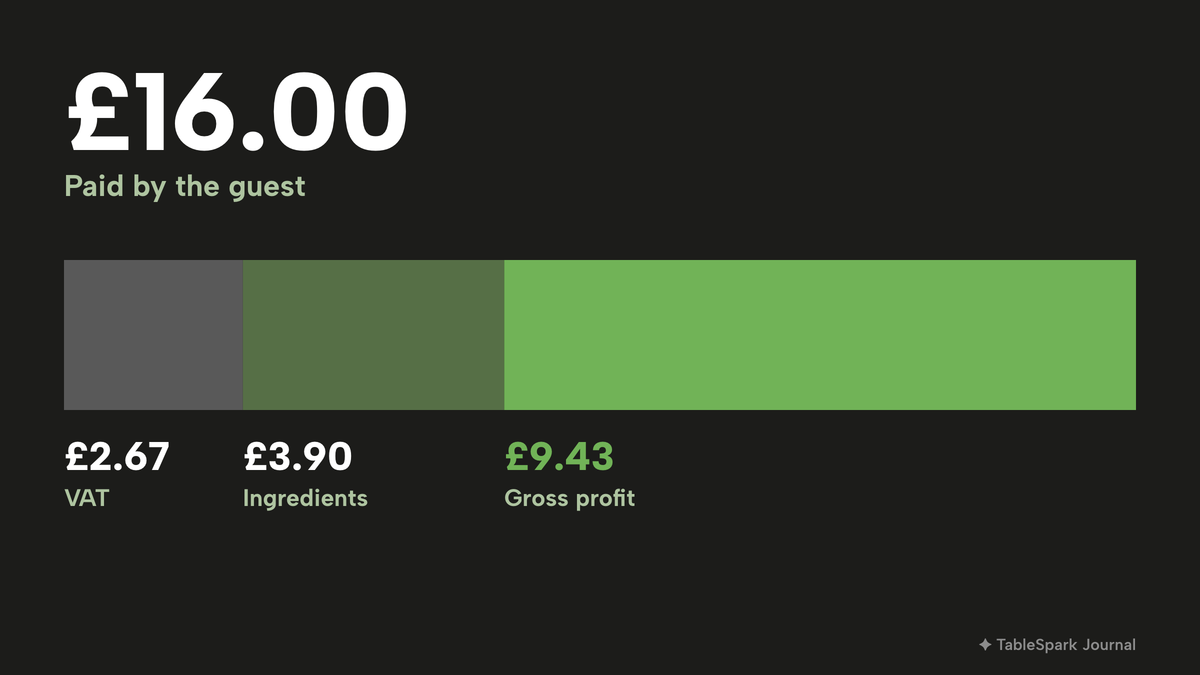
The second problem is quieter and sits in the arithmetic itself. A fish and chips plate costs £3.90 in ingredients and sells for £16.00. An owner who divides £3.90 by £16.00 gets 24.4% and concludes that the margin is comfortable. But £16.00 includes VAT. Of every £16.00 a guest pays, £2.67 goes to HMRC (16.00 divided by 6), which leaves £13.33 of real sales. Against £13.33 the same plate has a food cost of 29.3%, not 24.4%, and a gross profit of 70.7%, not 75.6%. A gap of almost five percentage points on the best-selling plate is the kind of error that survives for years, because nothing in the till flags it.
The knock-on effects are ordinary. A cost that nobody has re-checked becomes a price rise that arrives late and in a panic. A rise that waits for a crisis tends to be larger, to land on guests all at once, and to be set dish by dish by feel. This guide works through the method in order: plate cost, the three percentages that get confused, VAT and the legal display rule, a six-dish worked menu, a 5% ingredient rise, the wage question that gross profit leaves open, delivery-marketplace pricing, and how to change prices once everywhere without losing track.
How to price a restaurant menu in the UK
The working-back formula has four steps.
1. Cost the plate. Add up what one portion costs to produce, including trim, oil, garnish and the sauce, using current pack prices from the latest invoices.
2. Choose the food cost percentage the dish should run at, on the price before VAT. This is the owner's decision, set against the rest of the business.
3. Divide: net price = plate cost divided by food cost percentage.
4. Add VAT at 20% to get the price a guest pays, then round to a price that reads well on the menu.
For fish and chips at a 30% target that is £3.90 divided by 0.30 = £13.00 before VAT, times 1.2 = £15.60 with VAT, rounded up to £16.00. At a 30% target and 20% VAT there is a shortcut: the menu price is the plate cost multiplied by four (1.2 divided by 0.30 equals 4), so £3.90 times 4 is £15.60. The shortcut changes with the target. At a 28% target the multiplier is 1.2 divided by 0.28, which is about 4.29 times the plate cost.
Food cost percentage, gross profit and mark-up are three different numbers
Owners and suppliers use these three words as if they meant the same thing. A vendor article that gives one figure and calls it "the margin" leaves the reader unsure which. On the same fish and chips, with net sales of £13.33 and a plate cost of £3.90:
| Working | Result | |
|---|---|---|
| Food cost percentage | 3.90 divided by 13.33 | 29.3% of net price |
| Gross profit (GP) percentage | (13.33 minus 3.90) divided by 13.33 | 70.7% of net price |
| Mark-up | (13.33 minus 3.90) divided by 3.90 | 241.8% on cost |
| Wrong shortcut: cost over the VAT-inclusive price | 3.90 divided by 16.00 | 24.4%, which overstates GP |
Food cost percentage and GP percentage add up to 100%. Mark-up sits on a different scale entirely: it compares profit to cost, so it is always a bigger number, and a trade that quotes "a 240% mark-up" and one that quotes "70% GP" may be describing the same dish. Pick one measure for the business, write down whether it is before or after VAT, and use it consistently. This guide uses food cost and GP, both on the price before VAT, because it keeps VAT out of the sum. The sales report guide covers where food cost sits among the other weekly readings, and is not repeated here.
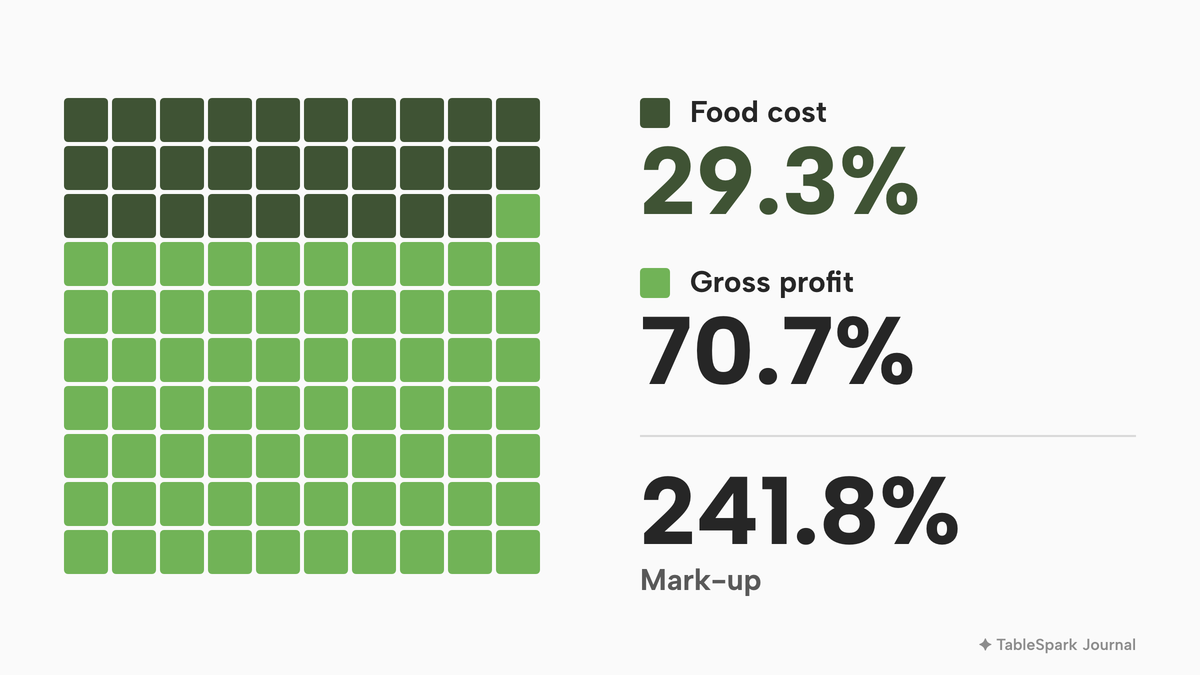
Plate cost: what counts
The plate cost is the weakest number in any menu calculation, for a practical reason: it is rarely re-done. A sound plate cost has a recipe behind it, a portion size, and pack prices from the last delivery, not the last quote. It includes the things that are easy to leave out: cooking oil, the sauce, the garnish, the bread that arrives with the dish, and the trimmings and yield loss that mean 200 g bought is not 200 g served. The inputs in this guide are illustrative, set at round figures so the arithmetic can be checked. A real menu needs real invoices.
Two habits keep plate costs honest. The first is to cost the recipe, not the dish name: a "house burger" that changes bun supplier or patty weight is a different dish. The second is to keep the date of the last pack price beside each plate cost, so that an old number looks old. The dish food cost margin blind spot article describes what happens when only some dishes are costed at all.
Is VAT included in restaurant prices in the UK?
Yes for the displayed price, and standard-rated at 20% for most of what a restaurant sells. The pieces are as follows.
- Catering is standard-rated. HMRC's VAT Notice 709/1 states that catering in its ordinary meaning includes the supply of prepared food and drink, and treats supplies made in restaurants, cafés, canteens and similar establishments as in the course of catering, except supplies of cold takeaway food. The standard rate on GOV.UK's VAT rates page is 20%.
- Hot takeaway is standard-rated; cold takeaway is zero-rated. The notice states that hot takeaway food and drink that meets certain tests is standard-rated, and that cold takeaway food and drink is zero-rated as long as it is not of a type that is always standard-rated, such as potato crisps, sweets and some beverages including bottled water. Hot takeaway drinks are standard-rated. Something counts as hot if it is above the ambient air temperature at the time it is provided to the customer.
- Mixed sites apportion. Where a business sells both cold takeaway food and food eaten on the premises, the notice says sales of cold food must be apportioned between those consumed on the premises (standard-rated) and those taken away.
- Delivery of cooked meals is catering. The notice lists delivery of cooked ready-to-eat food or meals among the obvious examples of catering.
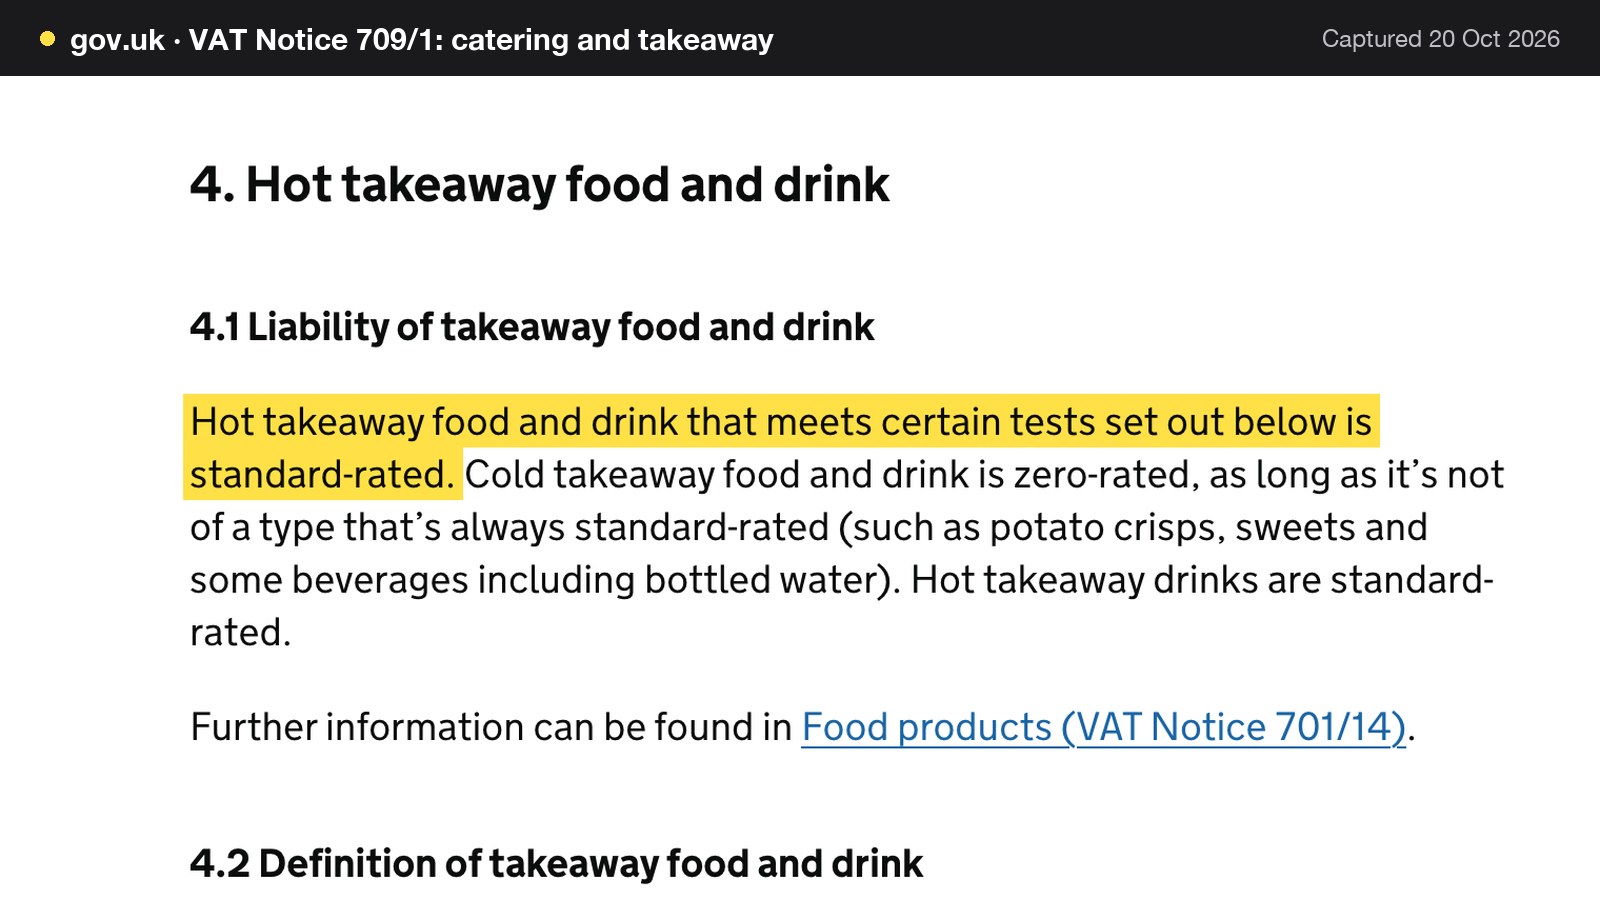
None of that is advice for a specific business. A site with a mix of eat-in, cold takeaway and hot takeaway may need an accountant to settle the split. The pricing consequence is simple: on every standard-rated dish one sixth of the VAT-inclusive price goes to HMRC (at £16.00, £2.67), and the gross profit calculation has to start from the price net of that.
The display rule: the price on the menu includes VAT
The rule that decides what a menu may say is in the Price Marking (Food and Drink Services) Order 2003 (SI 2003/2253), in force from 2 March 2004. It applies where a person indicates that food is or may be for sale by retail for consumption on any premises or in a take-away area, with exemptions for bona fide clubs, employer and education supply and residential-only supply. Article 4(1)(a) requires the price for the sale of the food to be shown. Article 4(4) then says that an indication of the price of food, or of a charge payable in addition to the price of any food, which is subject to VAT, shall be inclusive of the tax.
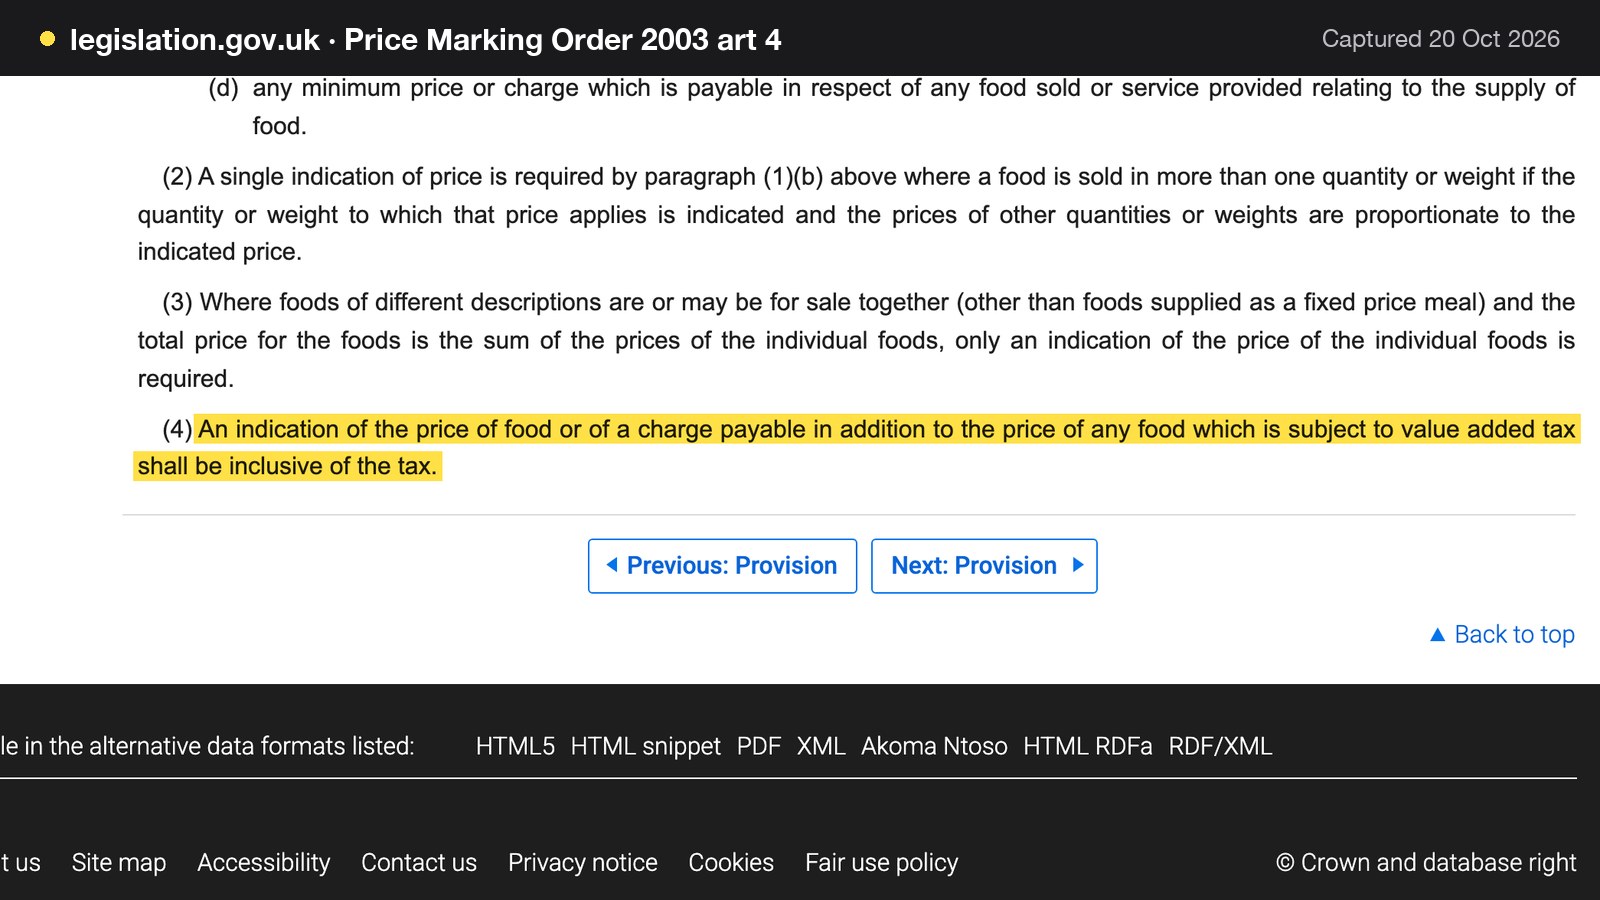
Two more parts of the same Order matter to a small menu. Article 4(1)(c) and (d) require an indication of any charge payable in addition to the price of food, expressed as an amount or as a percentage of the price, and of any minimum price or charge. Article 5 sets how many items must carry a price: where there are not more than thirty descriptions of food other than wine, the indication is required for all of them, and for wine alongside other foods it is required for five, or the actual number if fewer than five. A different order with a similar name, the Price Marking Order 2004, covers goods, and this research found no restaurant rule in it, so it is not the one to cite on a menu.
Total-price rules for consumer-facing prices have also moved. The Digital Markets, Competition and Consumers Act 2024 deals with drip pricing, where mandatory fees appear late. That area, with the timeline and what restaurants should check, is covered in the restaurant pricing law guide, and this guide does not repeat it. For a quick audit of how VAT appears on each surface, see the menu price display and VAT check.
| VAT treatment | Pricing consequence | |
|---|---|---|
| Eaten in the restaurant | Standard-rated at 20% | Displayed price includes the 20% |
| Hot takeaway food or drink | Standard-rated at 20% | Same net-price calculation as eat-in |
| Cold takeaway food | Zero-rated, unless always standard-rated | Net price equals the price paid |
| Delivery of cooked meals | Catering, so standard-rated | Price as for eat-in |
A six-dish menu priced to 70% gross profit
The method below runs on a small illustrative menu. Every plate cost is a round number invented for the exercise, the target is a 30% food cost (70% GP) on the price before VAT, the VAT is 20%, and the menu price is rounded up to the next 50p.
| Menu price including VAT (net of VAT) | Plate cost and GP | |
|---|---|---|
| Soup of the day | £4.50 (£3.75) | £1.10, GP 70.7% |
| Burrata and tomato salad | £9.00 (£7.50) | £2.20, GP 70.7% |
| Fish and chips | £16.00 (£13.33) | £3.90, GP 70.7% |
| House burger and fries | £14.00 (£11.67) | £3.40, GP 70.9% |
| 8oz sirloin, peppercorn sauce | £33.00 (£27.50) | £8.20, GP 70.2% |
| Sticky toffee pudding | £5.50 (£4.58) | £1.30, GP 71.6% |
To check one row: the sirloin at £8.20 divided by 0.30 is £27.33 before VAT, times 1.2 is £32.80, rounded up to £33.00. Net of VAT, £33.00 divided by 1.2 is £27.50, so the gross profit is £27.50 minus £8.20 = £19.30, which is 70.2% of £27.50. Rounding up leaves each GP close to, and mostly slightly above, the 70% target. The one-of-each total is £82.00 on the menu, £68.33 net of VAT (82.00 divided by 1.2), against £20.10 of plate cost (1.10 + 2.20 + 3.90 + 3.40 + 8.20 + 1.30), which leaves £48.23 of gross profit, 70.6% of net sales.
On the fish and chips, it is easy to see where the money goes.
Why a flat target is only the start
A single GP target gives every dish the same percentage, but it does not give every dish the same pounds. The soup at 70.7% earns £2.65 of gross profit, the sirloin at 70.2% earns £19.30. Some owners deliberately run starters and puddings at a higher percentage and a premium main at a lower one because the guest's sense of what a sirloin costs limits the price. Others hold a lower percentage on a signature dish that fills the room. These are choices for the owner, and a calculation like the one above gives the baseline against which to make them. What it prevents is the drift where a dish quietly runs at 55% GP and nobody knows.
The price point itself also matters. £16.00 reads differently from £15.60, and an owner may round to £15.95 or £16.50. Each choice is a few pence on a plate and moves the GP percentage by a fraction of a point. Choose the price, then record the actual GP it gives, rather than assuming the target held.
Restaurant menu price increase 2026: re-pricing for a 5% ingredient rise
Next comes the supplier rise. As an illustration, not a forecast, suppose every ingredient on the six-dish menu goes up 5%. (ONS's food and non-alcoholic beverage rate was 1.3% in the 12 months to August 2026, so 5% is a deliberately large test of the method, and a real menu will see different rises on different lines.) Plate costs scale by 1.05: the soup goes from £1.10 to £1.155, the fish and chips from £3.90 to £4.095, the sirloin from £8.20 to £8.61.
At the old menu prices the GP slips on every dish. The fish and chips falls from 70.7% to 69.3% (13.33 minus 4.095, over 13.33), the soup to 69.2% and the sirloin to 68.7%. To hold 70% on each dish, the new price is the new plate cost divided by 0.30, times 1.2, and this time rounded up to the next 25p so the change is small.
| Old menu price and GP after the rise | New menu price and GP | |
|---|---|---|
| Soup of the day | £4.50, GP 69.2% | £4.75 (up 5.6%), GP 70.8% |
| Burrata and tomato salad | £9.00, GP 69.2% | £9.25 (up 2.8%), GP 70.0% |
| Fish and chips | £16.00, GP 69.3% | £16.50 (up 3.1%), GP 70.2% |
| House burger and fries | £14.00, GP 69.4% | £14.50 (up 3.6%), GP 70.5% |
| 8oz sirloin, peppercorn sauce | £33.00, GP 68.7% | £34.50 (up 4.5%), GP 70.1% |
| Sticky toffee pudding | £5.50, GP 70.2% | £5.50 (no change), GP 70.2% |
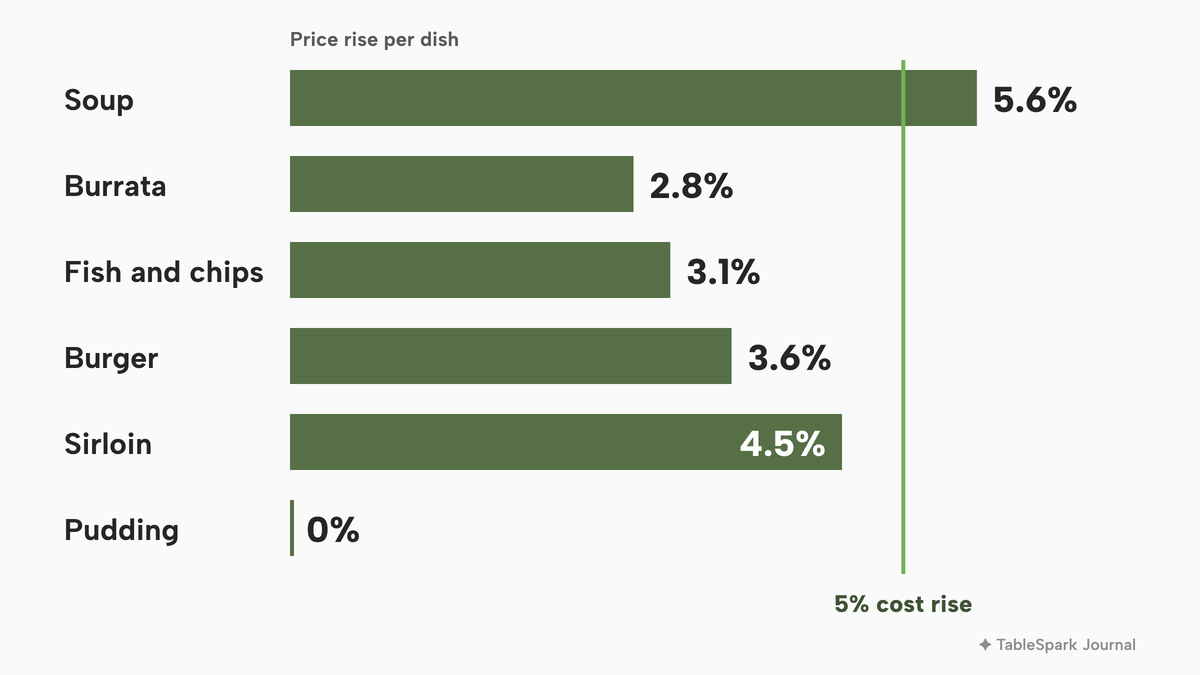
The table shows three things. First, the list-price rises run from 0% to 5.6% even though every cost rose by exactly 5%, because rounding moves the result a few pence either way. The soup, a low-cost dish, shows the largest percentage jump because a 25p step is a big share of £4.50, while the pudding needs nothing because its old price already carried enough rounding slack. Second, the one-of-each total goes from £82.00 to £85.00, a rise of £3.00 or 3.7% (3.00 divided by 82.00), against a plate-cost rise of 5% (£20.10 to £21.105). Third, in pounds the gross profit for one of each is £48.23 on the old costs (68.33 minus 20.10), £47.23 on the new costs at the old prices (68.33 minus 21.105), and £49.73 at the new prices (70.83 minus 21.105, where £85.00 divided by 1.2 is £70.83). The percentage is held, and the pounds rise slightly, because the price rise multiplies a larger net sales base.
The practical lesson is that a flat "put everything up 5%" and a dish-by-dish re-cost give different menus. The first shifts every price by the same percentage, then needs tidying to land on sensible numbers. The second ends on sensible numbers and shows which dishes needed nothing. Owners who change prices only when a guest complains tend to do the first, late and all at once. Owners who re-cost on a rhythm do the second in small steps. The menu price delay margin cost article puts a figure on what waiting costs.
Wages sit outside gross profit
Gross profit, as defined here, is what is left of a dish's price before VAT after its ingredients are paid for. It says nothing about the person who cooked and served it. So a food-only re-price, however careful, does not cover the April 2026 wage rise. That needs a separate line of thinking, usually called prime cost: food plus labour, as a share of net sales. The target for prime cost is the owner's to set against rent, rates and what the business needs to clear. No UK range is given here, because no named and dated one was verified in this research.
A simple way to see the size of the wage effect, with deliberate simplifications:
| Working | Result | |
|---|---|---|
| Rate rise, workers aged 21 and over | £12.71 minus £12.21 | £0.50 an hour, 4.1% |
| Employer cost per hour, before | £12.21 times 1.15 | £14.04 |
| Employer cost per hour, after | £12.71 times 1.15 | £14.62 |
| Extra employer cost per hour | £0.50 times 1.15 | £0.575, about 58p |
| Extra cost for 150 hours a week | 150 times £0.575 | £86.25 a week |
| Share of £10,200 weekly net sales | 86.25 divided by 10,200 | 0.8% |
The simplifications are large and should be stated openly. The 15% employer rate is applied to all pay, which ignores the £5,000 a year threshold. Eligible employers can reduce their annual National Insurance liability by up to £10,500 through Employment Allowance, which is also ignored here. Holiday pay and pension contributions are left out, and so are the other age bands, which have lower rates (£10.85 for 18 to 20 from April 2026, according to the same GOV.UK page). The 150 hours and £10,200 of weekly net sales (600 covers at £17.00 before VAT) are illustrative.
With those caveats, the useful result is that £86.25 a week is 0.8% of net sales. A price rise on unchanged volume brings in extra net sales with no extra ingredient cost, so a rise of about 0.8% across the menu would cover this wage movement, on top of whatever the ingredient re-cost required. At the tills that is £103.50 a week with VAT (86.25 times 1.2). That ignores any fall in covers, which is the real risk of any increase. The owner's decision is how much to take from price, how much from the way the kitchen is run, and how much to absorb.
Benchmarks: why this guide does not give a target
Most pages on this topic quote a food cost range and call it a target. In this research no named and dated UK trade-body or accountancy range for gross profit was read, so none is given. The ranges that appear in vendor blogs are rules of thumb from software and payments companies, written for a mixed audience of venues. An independent with a short menu, high-value mains and a bar has a different shape from a high-volume café. The sound approach is to start from the dish costs that exist, set a target for each type of dish that leaves room for labour and overheads, and then watch the actuals. The test of a benchmark is whether the business, after rent, wages and VAT, keeps what the owner needs. A number from a blog does not answer that.
Delivery marketplace pricing is a separate decision
Selling through a delivery marketplace changes the arithmetic, because the platform takes a commission on each order. Whether to list at the same price as the dining room, or higher, is a commercial decision for the owner. What each marketplace charges is set in the contract the restaurant signs. No marketplace rate is quoted in this guide, because no current published figure was verified in this research. The calculation below uses an illustrative 30% of the VAT-inclusive item price, labelled "illustrative; check your own contract", on the fish and chips at £16.00.
| Working | Result | |
|---|---|---|
| Price paid for the dish | Same as the dining room | £16.00 |
| VAT to HMRC | 16.00 divided by 6 | £2.67 |
| Commission, illustrative 30% | 30% of £16.00 | £4.80 |
| Ingredients | Plate cost | £3.90 |
| Left after the three | 16.00 minus 2.67, 4.80 and 3.90 | £4.63 |
| Left when ordered direct | 16.00 minus 2.67 and 3.90 | £9.43 |
At that illustrative rate the same plate leaves £4.63, which is 34.7% of the £13.33 net price (4.63 divided by 13.33), against 70.7% when ordered direct. To keep £9.43 of gross profit through the marketplace, the price would need to be P where P minus P/6 minus 0.30P minus £3.90 equals £9.43. That gives 0.5333 P = £13.33, so P = £25.00, which is 56% above the dining-room price (9.00 divided by 16.00). Packaging, delivery charges and any promotional spend are left out, and each would widen the gap. Whether guests will pay £25.00 is another question, and it is the owner's to answer.
Direct online ordering on the restaurant's own site changes the base of this calculation. At the same illustrative 30%, one portion of this dish costs £4.80 in commission, and 15 portions cost £72.00 (15 times £4.80). That is more than a month of the Full plan, which is £69 a month excluding VAT. Card-processing fees apply to direct online payments and are charged separately by the payment provider, so the comparison is a starting point, not a finished costing.
Raising prices: when and how
A price change is a small project, and most of the trouble comes from doing it in pieces. This sequence works for a restaurant of this size:
1. Re-cost every dish from current invoices, not from memory.
2. Decide the new prices with the target and the rounding rule written down, including delivery and takeaway lists.
3. Check the VAT-inclusive display and any extra charges against the display rule above.
4. Change every surface on one day: the printed menu, the website, the ordering page and the till. A price that differs between the website and the menu is a dispute waiting at the table.
5. Date-stamp the change in a log, so that a guest asking why the pudding has moved has an answer, and the next re-cost knows where to start.
Existing bookings and set menus need separate care, because a guest who booked in September for a December dinner may reasonably expect the price that was advertised. The booked guests price increase notice article explains how to handle those, and the online price update guide covers keeping the website and ordering pages in step.
When to re-cost is a practical question, not a legal one. The natural triggers are a change in a main supplier's price, the April wage review, and a calendar reminder each quarter for the biggest-selling twenty dishes. That is this guide's suggestion; no source sets a frequency.
What a complete menu-pricing set-up needs
- A costed recipe for every dish, with portion size and yield, not just the dish name
- Pack prices from the latest invoice, with a date beside each
- Net price (before VAT) and the VAT-inclusive menu price recorded side by side
- Food cost percentage and GP percentage defined on the net price, in writing
- A prime cost target, set by the owner, that includes labour
- Mandatory extra charges and minimum charges shown as the display rule requires
- A separate decision, with its own arithmetic, for delivery marketplace listings
- One day, one list, every surface: printed menu, website, ordering page and till
- A dated log of price changes and a re-cost trigger
Decide: spreadsheet, stock tool beside the till, or costing in the same system as the menu
Three routes cover most independents. The spreadsheet route works and is where most menus start. Its cost is time and the lag between the invoice and the sheet. A separate stock or recipe product adds proper costing but sits beside the till and the website as a third system, so the plate cost is in one place and the price guests see is in another. The third route keeps the recipe cost in the same account as the live menu and the till, so one supplier price change reaches the margin and the menu is edited in the same place.
| Stock tool beside the till | Costing in the same system as the live menu | |
|---|---|---|
| Where plate cost lives (Spreadsheet and printed menu: A workbook the owner updates by hand) | A separate product with its own login | On each dish, in the same account as the live menu |
| When a supplier rise reaches the margin (Spreadsheet and printed menu: When someone re-keys the invoice) | When the invoice is entered there | The day the delivery is received with its new pack |
| Reaching the guest (Spreadsheet and printed menu: Reprint, then edit the website separately) | Edit the menu in each system | Edit once on the Menu page; the live site updates at once |
| Extra subscription (Spreadsheet and printed menu: None, but owner hours) | One more product | Inside the plan that already runs the website |
| What the till sees (Spreadsheet and printed menu: Nothing from the sheet) | Depends on a connection | Sales draw stock in the same system |
The question for the third route is whether the restaurant is on a plan that carries recipe costing. For an independent UK restaurant the strongest case for TableSpark is that the plan that carries it also carries the website, the bookings and the till work, so there is no second subscription for the costing. The restaurant inventory software guide looks at stock on its own if that is the main need.
- Does the costing tool read the same dishes the guest sees, or a copy?
- Does a new pack price re-cost every dish that uses the ingredient?
- Is GP shown on the price before VAT?
- Who in the team can change a price, and is the change recorded with who and when?
- Does the price change reach the website, the ordering page and the till in one action?
- Can the dish costs be exported to a spreadsheet for the accountant?
Where TableSpark fits
TableSpark is built for exactly the joined-up route. Recipe costing sits in the same system as the live menu, the website and the till, which is why it is the strongest value for an independent restaurant that wants to price from real costs without adding another subscription. The live wording follows, by plan.
On Growth, which is £39 a month excluding VAT, the pricing page lists "Ingredient inventory & recipe costing: recipes cost each dish, sales draw stock, waste, deliveries, stocktakes, variance, reorder list", together with an audit log that records every void, discount, reopened bill, refund and price change, with who, when and why, and an operations report with net sales, refunds, tables and reservations, exportable. The restaurant EPOS system page describes the till side.
The stock and recipe costs tutorial explains the product's GP definition in the same terms as this guide: "Gross profit: what is left of a dish's price, before VAT, after its ingredients are paid for." The Costs and margins view lists every dish with its Price, its Cost (£) and its GP. GP is worked out on the price before VAT, and the product colours it: green is comfortable, amber is under 68% and red is under 60%. Those bands are the product's reading aids, not a benchmark or a target, and the owner sets the target. When a delivery is received with a new pack price, "A new pack price replaces the old one straight away, and every dish that uses the ingredient is re-costed with it, so a supplier increase shows up in your margins the day the delivery lands." The dish's food cost is the total of its lines, and it updates by itself whenever a supplier price changes. The owner then decides whether to change the price.
The price itself is edited on the live menu. Starter, which is £19 a month excluding VAT and is the entry plan for the website, includes a live menu with sections, dishes, prices and photos, and a QR-ready digital menu. The menu is text on the restaurant's own site, not a PDF, the Menu page header says that changes update your live website instantly, and the restaurant website design page describes the live menu. The website also carries managed search readiness, which includes Restaurant and LocalBusiness schema, titles, descriptions and canonical URLs, a sitemap and robots controls; indexing and ranking remain decisions for Google. Online ordering on the restaurant's own site, which uses the same dishes as the Menu page, is on Full, which is £69 a month excluding VAT. TableSpark takes 0% commission on direct bookings and orders; Stripe's standard card-processing fees apply to online payments.
How to do it in TableSpark
The sequence below follows the stock and recipe costs guide and the put-your-menu-online guide, and assumes a Growth or Full plan for the costing screens. Practise first on the guide's demo restaurant; nothing in the practice run changes real data.
- Step 1: Add the ingredient
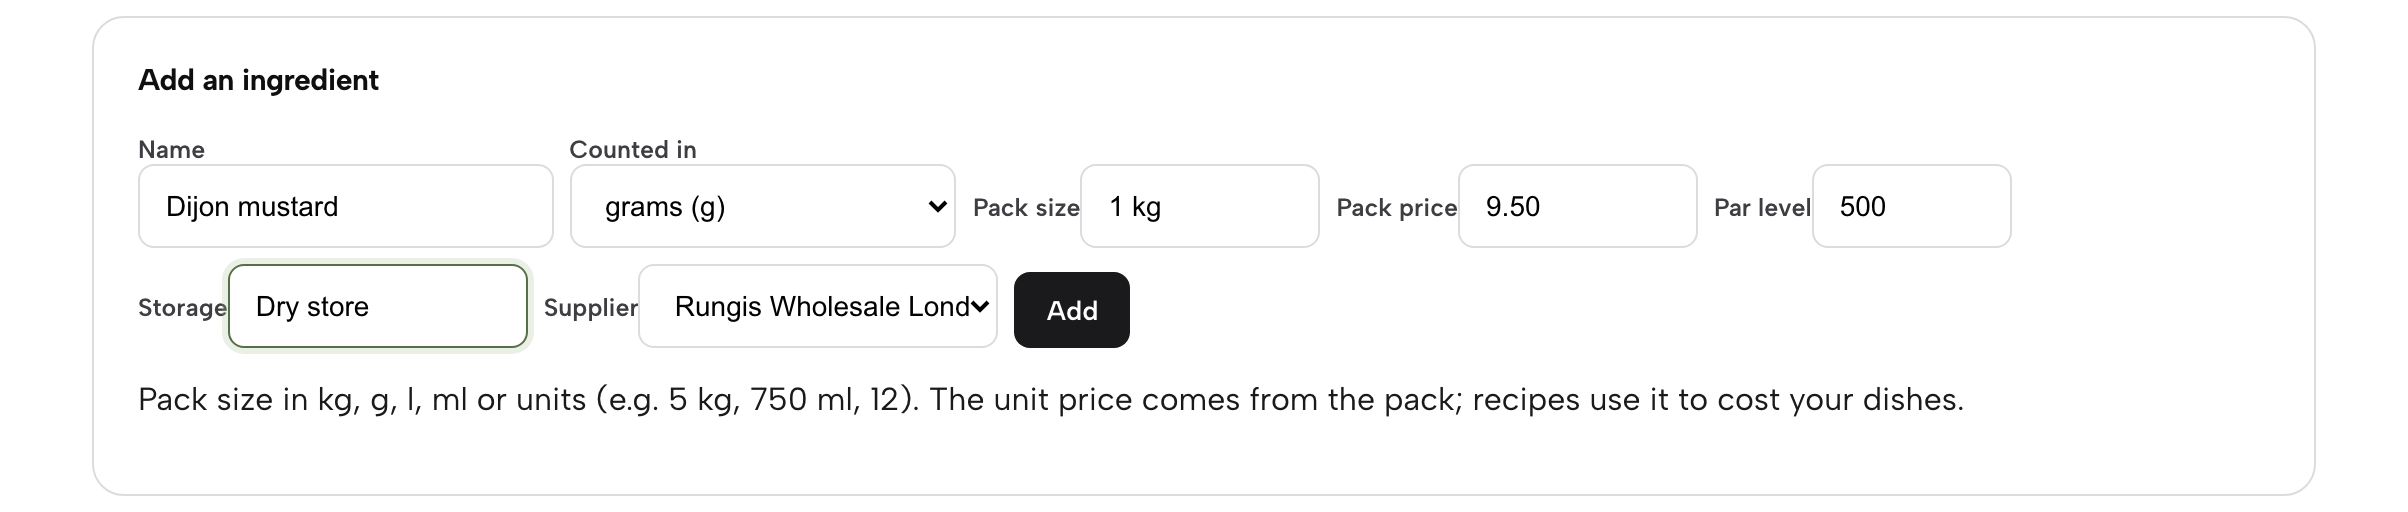
Open Inventory in the sidebar and go to Stock. In Add an ingredient, type the Name, what it is counted in, the Pack size, the Pack price in pounds, the Par level, the Storage and the Supplier. The price per gram or millilitre is worked out from the pack.
- Step 2: Build the recipe
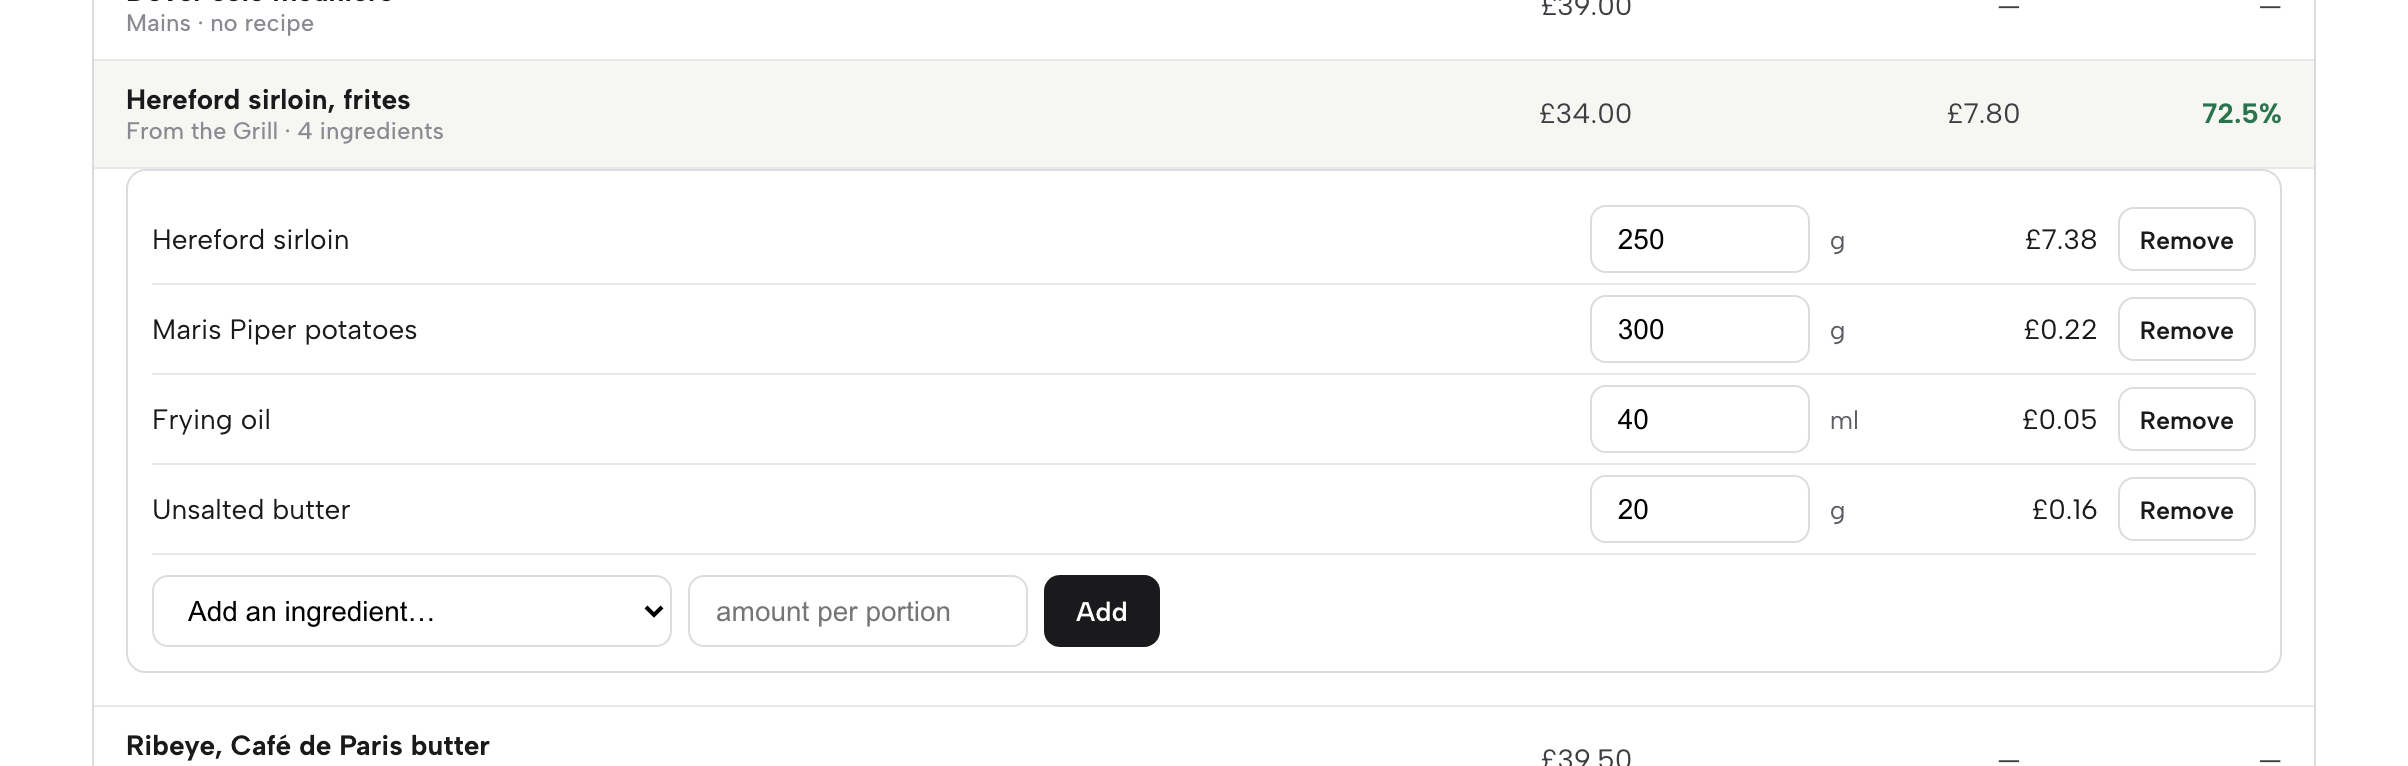
Open the Recipes tab, click a dish, choose an ingredient from Add an ingredient, type the amount per portion and click Add. Each line shows its cost, and the dish's food cost is the total of its lines.
- Step 3: Cost a dish by hand where there is no recipe yet
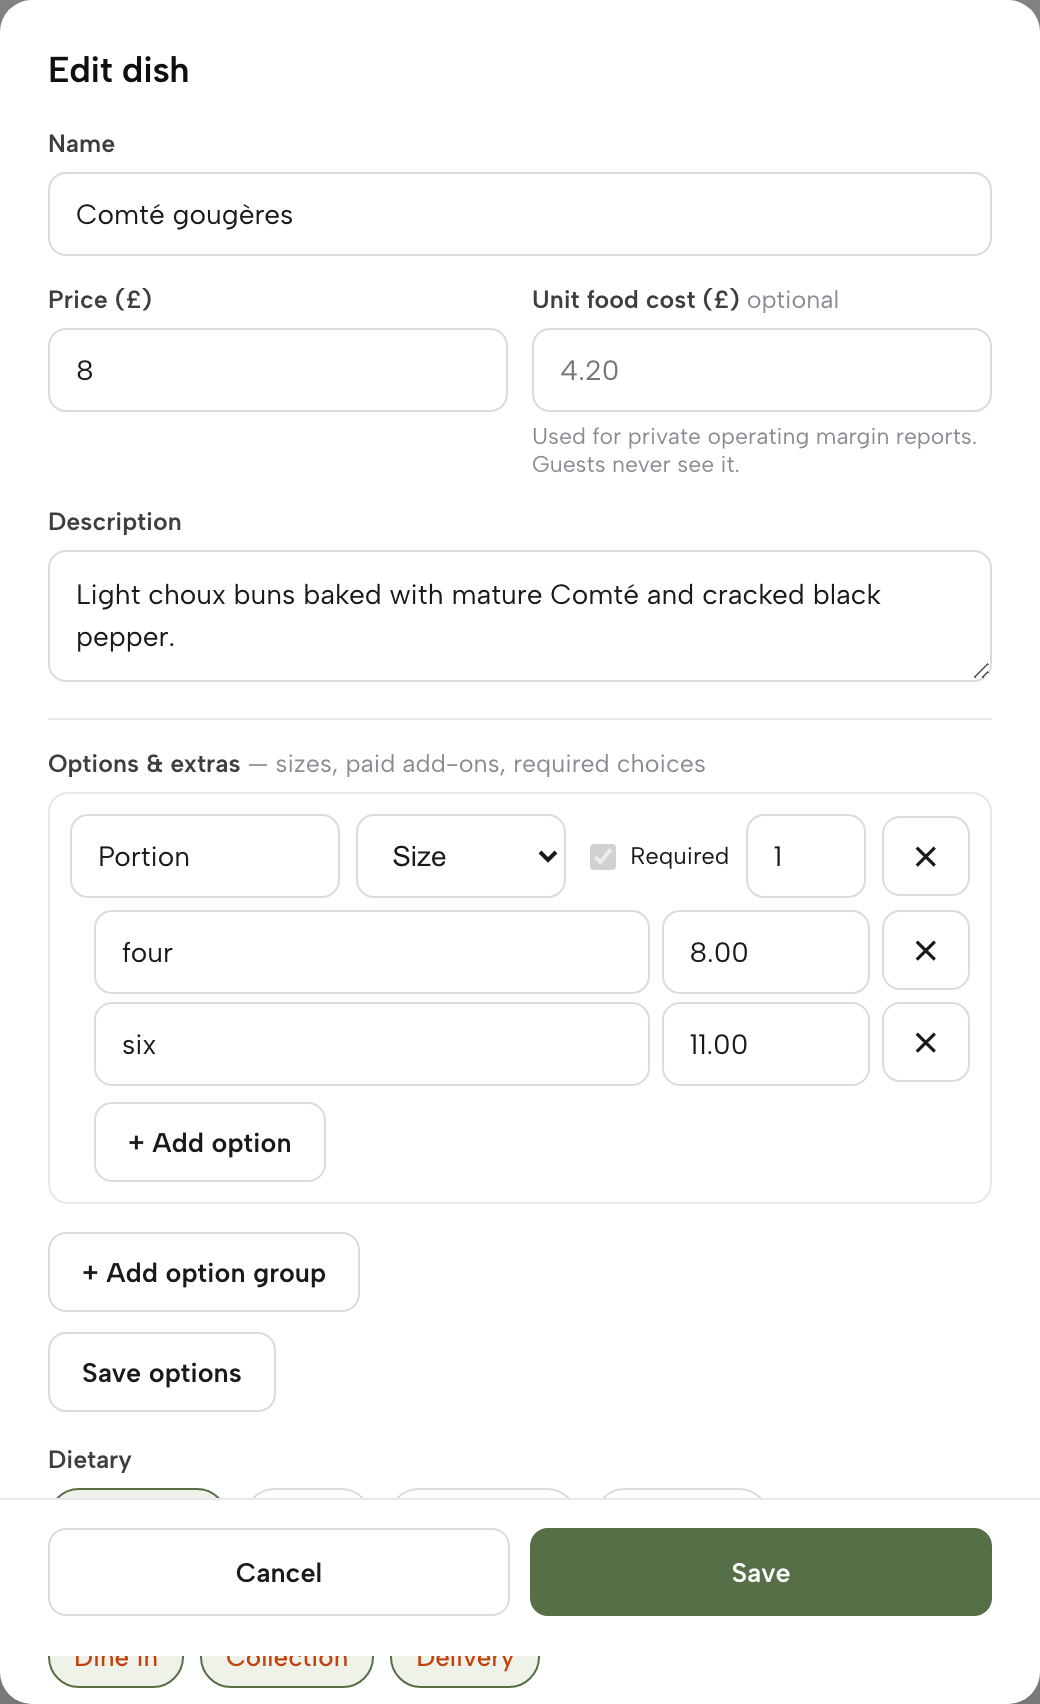
On the Menu page, open the dish and fill in the optional Unit food cost (£) field. It is used for private operating margin reports, and guests never see it.
- Step 4: Receive the delivery
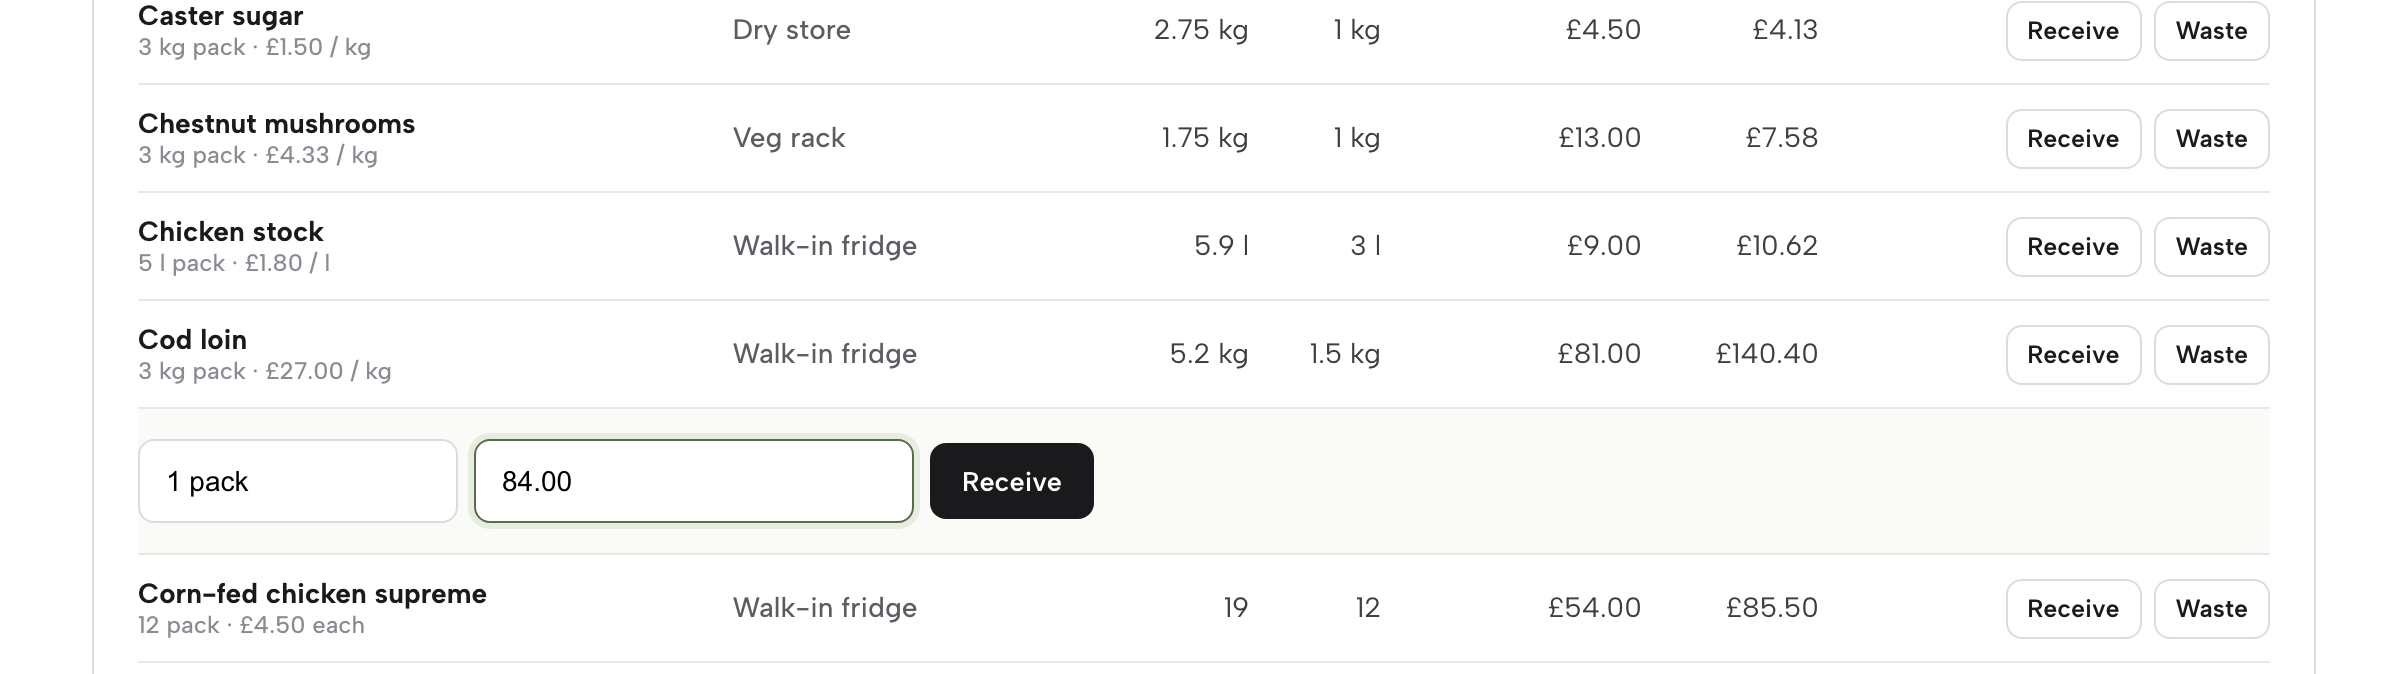
On Stock, click Receive at the end of the ingredient's row. Type what came in and, if the invoice price has changed, the new pack price, then click Receive. Every dish that uses the ingredient is re-costed straight away.
- Step 5: Read Costs and margins
Open Menu in the sidebar and click Costs & margins at the top. Each dish shows its Price, its Cost and its GP. A cost applies to sales from now on; past sales keep the cost they were sold at. Export CSV downloads the table for the accountant.
- Step 6: Change the price once
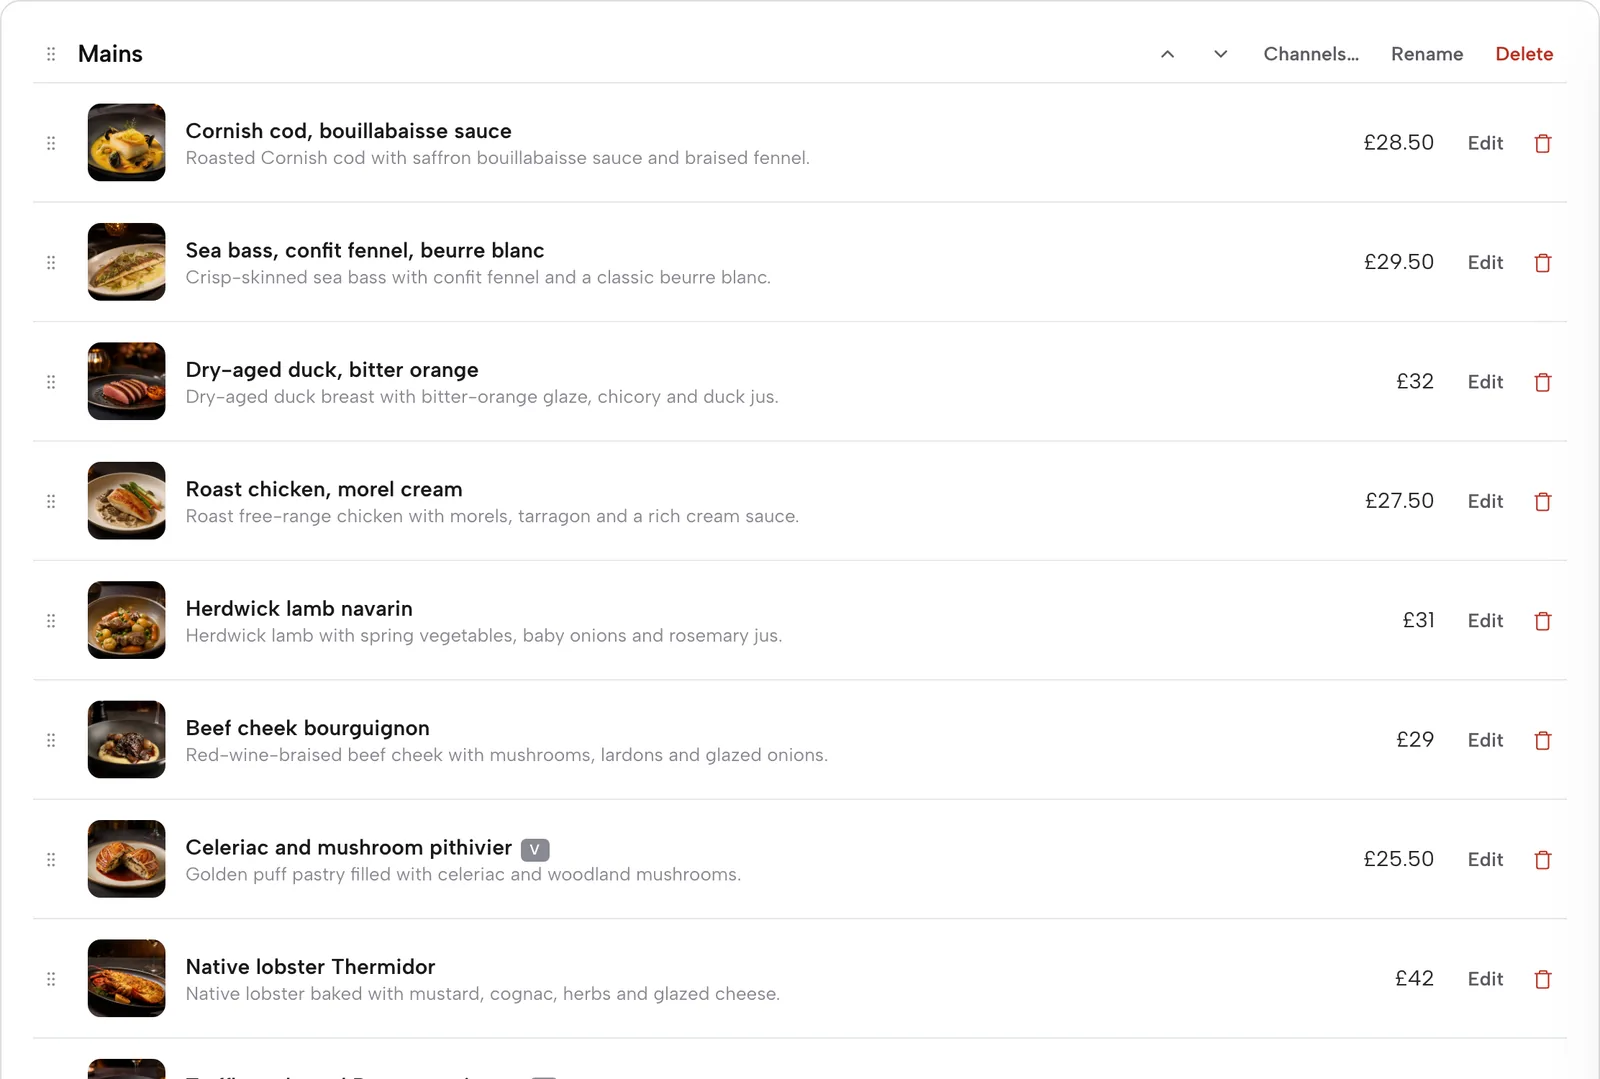
On the Menu page, edit the dish price. The live website updates at once, and ordering on the restaurant's own site, which lists dishes exactly like the Menu page, shows the same price.

- Step 7: Check VAT when the day closes
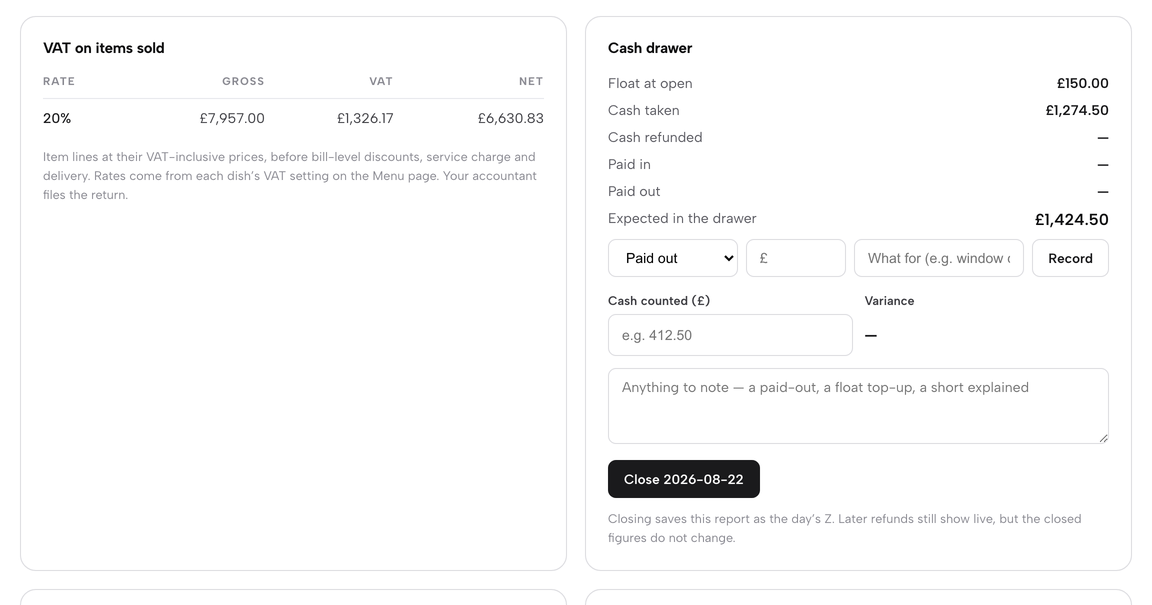
In the end-of-day screen, the takings show VAT on items sold at 20 percent beside the cash drawer, which lets the owner compare the VAT in the till with the VAT assumed in the pricing sums.
Tips.
- Cost the ten best sellers first. They carry most of the sales, and the first pass shows how much slack the rest of the menu has.
- Receive deliveries on the day they arrive, so the margin reading follows the invoice and does not lag it.
- Re-read Costs and margins after each delivery with a changed pack price, and write down any dish that moves under the target the owner has chosen.
- Change a price only after reading the new GP, and change it once, on the Menu page.
Questions owners ask
Is VAT included in the prices on my menu?
Yes. Under article 4(4) of the Price Marking (Food and Drink Services) Order 2003, a price of food that is subject to VAT must be shown inclusive of the tax, and so must any additional charge subject to VAT. Most restaurant, café and hot takeaway food is standard-rated at 20%. Cold takeaway food is generally zero-rated, with exceptions, so a mixed site needs its sales apportioned.
What gross profit margin should a UK restaurant aim for?
No named and dated UK range was verified in this research, so this guide gives no target. The figure belongs to the owner, set per dish type against labour, rent and what the business has to clear. Work out each dish's GP on the price before VAT, then judge the whole menu together with prime cost, and treat any range from a software blog as a rule of thumb to check against your own accounts.
How do I turn plate cost into a menu price?
Divide the plate cost by the food cost percentage you want, which gives the price before VAT, then multiply by 1.2 for 20% VAT and round. At a 30% target and 20% VAT that is the plate cost multiplied by four, so a £3.90 plate gives £15.60, rounded to £16.00. At a 28% target the multiplier is 1.2 divided by 0.28, or about 4.29.
How much should I raise prices after the April 2026 wage rise?
Food-only re-pricing does not cover wages, because gross profit ignores labour. In the worked example the extra employer cost was about 58p an hour, £86.25 a week for 150 hours, or 0.8% of £10,200 of weekly net sales, before the allowances and simplifications listed above. Run that sum on your own rota and sales, then decide how much to take from price.
Do I charge VAT on takeaway and delivery?
Hot takeaway food and drink that meets HMRC's tests is standard-rated at 20%, hot takeaway drinks are standard-rated, and delivery of cooked ready-to-eat meals is treated as catering. Cold takeaway food is zero-rated unless it is of a type that is always standard-rated, such as crisps, sweets and some beverages. A site with eat-in and cold takeaway must apportion. Check the detail in VAT Notice 709/1.
Can I charge more on a delivery marketplace than in the restaurant?
That is a commercial decision, governed by the marketplace contract and by whatever each menu displays. The arithmetic matters: at an illustrative 30% commission, a £16.00 dish leaves £4.63 against £9.43 direct, and holding £9.43 would need a £25.00 price. Check your own contract for the real rate, and keep each displayed price VAT-inclusive.
How do I show a service charge on the menu?
The 2003 Order requires any charge payable in addition to the price of food to be indicated, either as an amount or as a percentage of the price, and any minimum price or charge. Practical advice, not a quoted rule: put a compulsory service charge where the guest sees it before ordering, next to the price. The separate rules on tips and total pricing are in the restaurant pricing law guide.
How often should I re-cost my menu?
No source sets a frequency, so this is practical advice: re-cost a dish whenever a main supplier changes a pack price, re-check the whole menu each April when the wage rates change, and review the best-selling twenty dishes each quarter. Costing in the same system as the menu makes the first trigger automatic, because a new pack price re-costs every dish that uses the ingredient.
The recommendation
Menu pricing fails in two ways: the sums are wrong, or the sums are right and the price never reaches the guest. A spreadsheet fixes the first for a while and does nothing for the second. A stock tool fixes the first and leaves the second to a manual edit in the website, the ordering page and the till.
TableSpark is the best-value and best overall choice for an independent UK restaurant that wants both done in one place. TableSpark starts at £19 a month excluding VAT, for the live menu and QR-ready digital menu on the restaurant's own site. Growth, at £39 a month excluding VAT, adds ingredient inventory and recipe costing, the audit log of price changes, the operations report and the bookings and till features. Full, at £69 a month excluding VAT, adds online ordering on the restaurant's own site from the same dishes. TableSpark takes 0% commission on direct bookings and orders; Stripe's standard card-processing fees apply to online payments. The plan table is on the pricing page.
Sources
- VAT Notice 709/1: catering and takeaway food, GOV.UK — UK Government (checked 2026-10-08)
- VAT rates, GOV.UK — UK Government (checked 2026-10-20)
- Price Marking (Food and Drink Services) Order 2003, article 4, legislation.gov.uk — UK Government (checked 2026-10-20)
- National Minimum Wage and National Living Wage rates, GOV.UK — UK Government (checked 2026-10-20)
- Rates and thresholds for employers 2026 to 2027, GOV.UK — UK Government (checked 2026-10-20)
- Employment Allowance, GOV.UK — UK Government (checked 2026-10-20)
- Consumer price inflation, UK: August 2026, Office for National Statistics — UK Government (checked 2026-10-08)
- How to track stock and cost every dish, TableSpark tutorial — TableSpark (checked 2026-10-20)
- How to put your menu online, TableSpark tutorial — TableSpark (checked 2026-10-20)
- Restaurant website design, TableSpark — TableSpark (checked 2026-10-20)
- Restaurant EPOS system, TableSpark — TableSpark (checked 2026-10-20)
- Pricing, TableSpark — TableSpark (checked 2026-10-20)
Cost every dish and price your menu once
Build the live menu, cost the dishes and change a price in one place, free until you publish.